
- Multi-Asset Portfolio Manager
United States, Intermediary
Change
This is a monthly snapshot of Wellington Solutions’ asset allocation views as of October 2026. It covers global equities, bonds and commodities and complements the more detailed analysis we share in our Quarterly Asset Allocation Outlook.
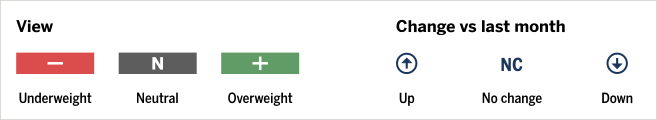
*Please note that we use a more detailed key in our Quarterly Asset Allocation Outlook.
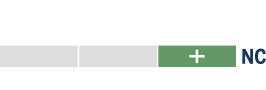
We maintain a modest overweight view on global equities, although our stance is more measured than earlier in the year. In our view, resilient nominal growth, healthy earnings and AI-related investment continue to support the fundamental backdrop. However, we think that earnings growth is likely to moderate, while higher financing costs and greater sensitivity to interest rates create a less favourable near-term risk/reward balance. Regionally, we continue to favour emerging markets (EM) over the UK but have narrowed this preference, while maintaining a neutral view elsewhere.
US
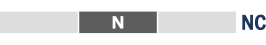
We retain a neutral view on US equities. The recent valuation adjustment has improved the entry point, while earnings and AI-related investment remain supportive. However, earnings expectations set a relatively high hurdle, and the level of projected issuance could create an additional headwind. Questions around the cost and financing of the AI capex cycle also warrant caution. We therefore remain constructive on the fundamentals but do not see sufficient relative upside to support an overweight stance.
Europe ex-UK
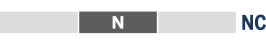
Our neutral view on Europe ex-UK equities remains unchanged. The region faces a weaker earnings growth outlook than some other developed markets, while renewed widening in French sovereign spreads could weigh on sentiment towards regional risk assets. European companies may also be vulnerable to higher gas prices should geopolitical tensions in the Middle East continue to escalate. Taken together, these risks leave us without a sufficiently compelling case to adopt a more positive view.
UK
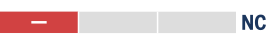
We retain an underweight view on UK equities. The UK continues to lag other markets in terms of earnings growth. However, our view has become more measured as valuations have improved and potential policy catalysts could support a rerating. We therefore maintain our underweight view, but by a narrower margin than previously.
Japan
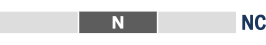
We still have a neutral view on Japanese equities. Risks from rising interest rates and a higher yen have partly subsided, while broad-based earnings growth, corporate reform and the reflationary backdrop remain supportive. While we are becoming more constructive, we would look for a more attractive entry point before considering an overweight stance.
Emerging markets
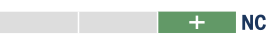
We remain overweight EM equities, although we have moderated our stance. Attractive valuations and exposure to North Asian AI and semiconductor supply chains continue to support the longer-term outlook. However, regional outperformance remains narrow, with earnings growth increasingly concentrated among Asian AI beneficiaries rather than reflecting a broader EM story. Higher oil prices and US yields also reduce the policy cushion available to parts of the EM universe, supporting a more measured view.
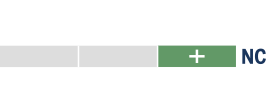
We remain modestly overweight global duration. Following the recent repricing, elevated nominal and real yields offer a more attractive 12-month risk/reward profile, with a higher hurdle for a sustained further rise in yields. Market pricing assumes resilient AI-led growth, broader productivity gains, elevated term premia and relatively hawkish central banks. While yields could rise further, we believe these assumptions may become increasingly difficult to sustain, particularly if high financing costs and energy prices begin to weigh more materially on growth.
US
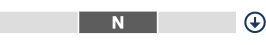
Our view on US rates has shifted from overweight to neutral. Yield levels remain attractive, but signs of resilience in the labour market and the potential for greater passthrough to core inflation could lead markets to reassess the inflation outlook, informing our neutral stance.
Europe ex-UK
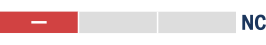
We remain underweight Europe ex-UK government bonds, a stance underpinned by our view on Germany. Early signs of increased transport and social infrastructure spending point to a gradual fiscal impulse, which could place further upward pressure on Bund yields. France’s fiscal outlook remains challenging, with political pressures limiting the prospects for credible consolidation. We no longer see the need to adopt an underweight stance in relation to France given the significant widening in French sovereign spreads. However, we remain cautious and would look for a more attractive entry point before re-engaging.
UK
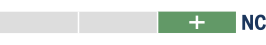
We maintain our overweight perspective on UK rates relative to Germany. UK rates already reflect considerable fiscal and monetary risk, while the government has signalled a greater focus on market credibility and addressing supply-side constraints. Softer labour market conditions and contained second-round inflation effects could also lead markets to price fewer rate hikes than currently expected, providing scope for UK term premia and policy expectations to ease.
Japan
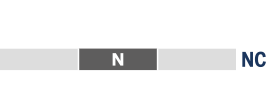
We retain a neutral view on Japanese government bonds. Fiscal policy remains an important headwind and further action from the Bank of Japan may be needed to restore policy credibility.
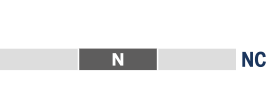
We remain neutral on credit. In our opinion, recent spread widening across investment-grade, high-yield and EM debt has created pockets of value. However, we would need to see further widening before adopting a more positive broad market stance. AI-related financing is also driving greater differentiation as investors scrutinise funding needs, cash generation and returns on infrastructure spending.
Investment-grade credit
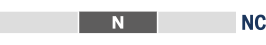
Our investment-grade credit view remains neutral. Regionally, we see a relatively more favourable backdrop in the US than in Europe. However, substantial financing requirements remain a concern as investors seek greater clarity on leverage targets, minimum cash balances and future issuance. Overall, we do not yet see a sufficiently compelling case for a more positive broad market view.
High yield
We retain a neutral view on high yield, with a preference for the US over Europe. While recent widening has improved European valuations, fiscal and political uncertainty and the prospect of increased “fallen angel” supply remain headwinds. We would look for greater stability in European rates and sovereign markets before becoming more constructive and we think it is preferable to remain on the sidelines for now.
Emerging markets
We remain neutral on EM debt. Spread widening has created areas of value, leaving us relatively more constructive than in other parts of credit. However, tighter global financial conditions remain a risk, while outcomes are likely to be driven more by differences across countries than by broad market exposure.
Our view on commodities remains neutral. The still escalating Middle East conflict has lifted energy prices and added to uncertainty, leaving us on the sidelines in oil. For gold, central bank purchases and ETF flows are providing less consistent support, while higher interest rates remain an additional headwind. We therefore retain a neutral stance.
These asset allocation views are produced by Wellington Solutions, which provides client-centred investment solutions, research and advice ranging from whole portfolio solutions to bespoke single asset class and advisory partnerships. Our solutions platform incorporates expertise across multi-asset, fundamental factor investing and thematic approaches to deliver across a range of client outcomes and objectives. If you wish to discuss your investment challenges, and how Wellington Solutions can help, please contact your Wellington relationship manager or solutions@wellington.com.
Disclosure
For professional and institutional investors only. All investing involves risk. Investment markets are subject to economic, regulatory, market sentiment and political risks. All investors should consider the risks that may impact their capital, before investing. The value of your investment may become worth more or less than at the time of the original investment. If the strategies do not perform as expected, if opportunities to implement them do not arise, or if the team does not implement its investment strategies successfully, then a strategy may underperform or experience losses. Past performance is not a reliable indicator of future results and investments can lose value.
This material is prepared for, and authorised for internal use by, designated institutional and professional investors and their consultants or for such other use as may be authorised by Wellington Management. This material and/or its contents are current at the time of writing and may not be reproduced or distributed in whole or in part, for any purpose, without the express written consent of Wellington Management. This material is not intended to constitute investment advice or an offer to sell, or the solicitation of an offer to purchase shares or other securities. Investors should always obtain and read an up-to-date investment services description or prospectus before deciding whether to appoint an investment manager or to invest in a fund.
Any views expressed herein are those of the Wellington Solutions, are based on available information and are subject to change without notice. Individual portfolio management teams may hold different views and may make different investment decisions for different clients. While any third-party data used is considered reliable, its accuracy is not guaranteed.
This material represents an assessment of the market and economic environment at a specific point in time and is not intended to be a forecast of future events, or a guarantee of future results. Forward-looking statements are subject to certain risks and uncertainties. Actual results, performance or achievements may differ materially from those expressed or implied. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions. It should also not be construed as advice meeting the particular investment needs of any investor. Past performance does not guarantee future results.
The views expressed are those of the authors at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.
Experts







Quarterly Market Review — 3Q26
A quarterly update on equity, fixed income, currency, and commodity markets.
By