European high yield: time for selectivity

5 min read
2027-10-19
Archived info
Archived pieces remain available on the site. Please consider the publish date while reading these older pieces.
Multiple authors
1407099-European high yield

Key points

  • European high yield remains a structurally attractive proposition for many investors, but compressed spreads and an extended period of strong performance point to the need for greater caution.
  • From a wider portfolio perspective, this less favourable backdrop implies the need for a greater emphasis on time horizon and careful calibration of asset allocation decisions.
  • Active management may be key to help mitigate potential volatility and gain targeted exposure to the select opportunities we still see across certain sectors and individual issuers.

Allocating to European high-yield bonds has been a sound strategy over recent years but many existing investors are asking whether it is time to take stock, while new investors are weighing the risk-return trade-offs.

In our view, the structural appeal of the asset class remains robust, supported by a consistent trend towards higher-quality issuance and attractive income potential. However, tight valuations mean that relying on spread compression for returns may no longer be a winning strategy.

Instead, we think it is time for a different approach that focuses on disciplined credit selection to capture the opportunities a more diverging market may bring.

Structurally stronger, but less favourable starting point

European high yield has delivered strong returns in recent years. Investors have benefited from attractive income, resilient corporate fundamentals and a market that has continued to improve in quality, with BB-rated issuers now representing a larger share of the index. Moreover, the asset class continues to offer attractive diversification potential, especially for investors looking to diversify away from the US.

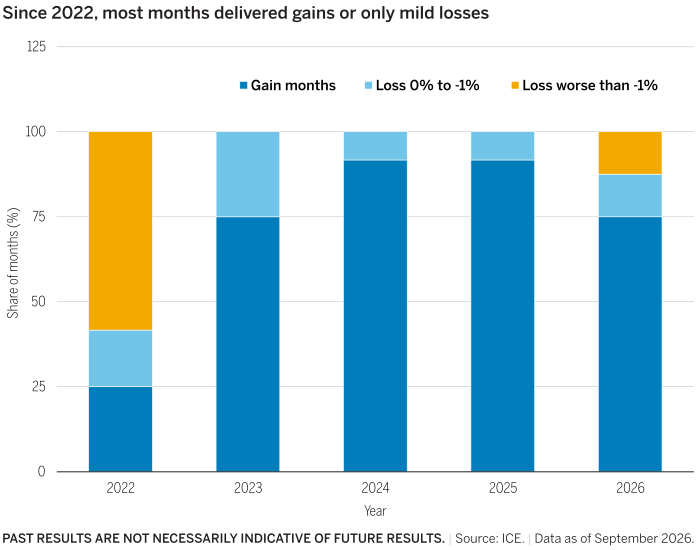
However, after several years of strong returns, spreads are now at historically tight levels. In our view, this spread compression should give investors pause for thought. In fact, since the last major market drawdown in 2022, we have experienced only a few periods of market weakness. with the asset class generating positive returns across most months, as Figure 1 shows. Moreover, most negative months have involved only modest losses.

Figure 1

1407099-european-high-yield

That strong performance has changed the starting point for investors considering an allocation to high yield now, with less scope for further broad-based compression and a smaller valuation cushion if conditions deteriorate.

Should investors wait for wider spreads?

While many investors have historically used spread levels as the key indicator for timing an entry point to high yield, historical data suggests that tight starting spreads have not necessarily led to poor long-term outcomes (5 – 10+ years), implying that investors need to consider the time horizon of any allocation more carefully.

Wider spreads generally produce stronger subsequent excess returns, in particular over more tactical time horizons (1 – 3 years), but spread levels at investment inception tend to become less important over longer periods as excess returns gradually converge.

Moreover, while wider spreads offer a more attractive entry point for tactical investors, market dislocations are notoriously difficult to time and they can reverse quickly. Waiting also carries an opportunity cost, especially in an environment where the asset class remains supported by stronger-than-expected nominal growth. Investors who remain unallocated may forego the income generated by the asset class while waiting for a better entry point that may not arrive for some time.

We see two key implications:

  1. For strategic investors, we believe it generally makes sense to maintain exposure, while retaining the necessary flexibility to add risk when valuations become more attractive. We also believe there is value in allocating to a manager with spread sensitivity embedded in their investment process to consider near-term market dynamics.
  2. For tactical allocations, the case for waiting stands, but given timing and opportunity cost, a gradual allocation approach may be helpful as it reduces the importance of any single entry point.

A final but vital point is that even with tight spreads, the all-in yield available from European high yield remains meaningful. That meaningful all-in yield provides a cushion against spread widening and helps mitigate the impact of moderate price volatility.

Tight spreads do not necessarily mean a lack of opportunity

Headline spread levels also conceal dispersion across the market. Many higher-quality BB- and B-rated securities are tightly valued. In some cases, the additional yield available over investment-grade bonds does not adequately compensate investors for the increase in credit risk. Further down the rating spectrum, valuations are more varied. Some lower-rated securities offer attractive compensation, while others face genuine refinancing, liquidity or fundamental risks.

In our view, this more complex backdrop should favour an active approach. Tilting portfolios away from tight spreads towards the select opportunities that are currently still available is not as simple as moving down in quality. The challenge is to identify issuers where the market is overcompensating investors for manageable risks, while avoiding securities that are cheap for good reasons. In our view, tackling that challenge involves more than ever the ability to undertake both detailed issuer and capital-structure analysis. It also requires an in-depth understanding of the broader industry and sector dynamics in which issuers operate.

Where are we seeing opportunities?

Rather than stretching for incremental yield in the most expensive areas of the market, we think investors would be served by seeking exposure to segments and issuers that the market tends to overlook, where valuations better reflect the underlying risks. These include:

  • Lower-rated credits where our analysis supports a credible path to refinancing, deleveraging or an improvement in credit quality. The emphasis is not on the rating itself, but on whether the potential return adequately compensates investors for the downside risk.
  • Sectors that are currently less favoured by a market focused on the AI theme, but where we think fundamentals are robust. These include select commercial real estate issuers with strong asset quality and refinancing capacity that are supported by resilient demand for high-quality office space in certain markets, and defensively orientated pharma companies with strong competitive moats and cash-flow dynamics.

At the same time, we think moving into select investment-grade bonds may offer better risk-adjusted value than tightly priced BB securities, given a combination of similar income with greater downside resilience.

Getting the balance right

Tight spreads and a long run of strong performance point to the need for investors to take a different approach to European high yield: one that recognises the structural appeal of the asset class but also the need for greater risk mitigation and active management. In practice, we believe:

  • Investors need to think more carefully about their time horizon, maintaining strategic exposures but adopting a gradual approach for more tactical allocations.
  • Investors should favour an active approach that drills down to sector and issuer level to mitigate risk and take advantage of the select opportunities we see in this more complex environment.
The views expressed are those of the author at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.
ExpertS

Read more from our experts

Past results are not necessarily indicative of future results and an investment can lose value. Funds returns are shown net of fees. Source: Wellington Management

© 2026 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. The Overall Morningstar Rating for a fund is derived from a weighted average of the three, five, and ten year (if applicable) ratings, based on risk-adjusted return. Past performance is no guarantee of future results.

The content within this page is issued by Wellington Management Singapore Pte Ltd (UEN: 201415544E) (WMS). This advertisement or publication has not been reviewed by the Monetary Authority of Singapore. Information contained on this website is provided for information purposes and does not constitute financial advice or recommendation in any security including but not limited to, share in the funds and is prepared without regard to the specific objectives, financial situation or needs of any particular person. 

Investment in the funds described on this website carries a substantial degree of risk and places an investor’s capital at risk. The price and value of investments is not guaranteed. The value of the shares of the funds and the income accruing to them, if any, and may fall or rise. An investor may not get back the original amount invested and an investor may lose all of their investment. Investment in the funds described on this website is not suitable for all investors. Investors should read the prospectus and the Product Highlights Sheet of the respective fund and seek financial advice before deciding whether to purchase shares in any fund. Past performance or any economic trends or forecast, are not necessarily indicative of future performance. Some of the funds described on this website may use or invest in financial derivative instruments for portfolio management and hedging purposes. Investments in the funds are subject to investment risks, including the possible loss of the principal amount invested. None of the funds listed on this website guarantees distributions and distributions may fluctuate and may be paid out of capital. Past distributions are not necessarily indicative of future trends, which may be lower. Please note that payment of distributions out of capital effectively amounts to a return or withdrawal of the principal amount invested or of net capital gains attributable to that principal amount. Actual distribution of income, net capital gains and/or capital will be at the manager’s absolute discretion. Payments on dividends may result in a reduction of NAV per share of the funds. The preceding paragraph is only applicable if the fund intends to pay dividends/ distributions. Performance with preliminary charge (sales charge) is calculated on a NAV to NAV basis, net of 5% preliminary charge (initial sales charge). Unless stated otherwise data is as at previous month end.
Subscriptions may only be made on the basis of the latest prospectus and Product Highlights Sheet, and they can be obtained from WMS or fund distributors upon request.

This material may not be reproduced or distributed, in whole or in part, without the express written consent of Wellington Management.