- Fixed Income Portfolio Manager
Skip to main content
- Funds
- Capabilities
- Insights
- About Us
FEATURED EQUITY FUNDS
FEATURED FIXED INCOME FUNDS
Asset classes
Singapore, Individual
Changechevron_rightFEATURED EQUITY FUNDS
FEATURED FIXED INCOME FUNDS
Asset classes
The views expressed are those of the author at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed.
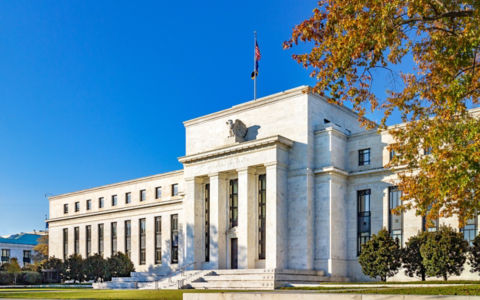
The Federal Open Market Committee (FOMC) once again kept interest rates on hold at its March policy meeting. In its updated projections, the US Federal Reserve (Fed) downgraded its growth forecasts and increased its inflation and unemployment rate forecasts, with the median Committee member still expecting to cut rates twice by the end of this year. Market participants also continue to anticipate a resumption of rate cuts later this year, based on futures pricing.
The range of outcomes for the economy appears quite wide given policy uncertainty, particularly around tariffs. In his prepared statement at the post-meeting press conference, Fed Chair Jerome Powell acknowledged weaker consumer spending patterns but asserted that the Fed is “well-positioned to wait for greater clarity.”
With inflation still elevated at levels that I would describe as uncomfortable for consumers and policymakers, it makes sense for the Fed to stay on hold for the time being, despite the emergence of downside growth risks. We have not yet witnessed material weakness in labor markets, as jobless claims remain stable at low levels and the unemployment rate hovers around 4%. The drop-off in labor demand from weaker growth is likely to be matched by reduced labor supply from immigration policies as well as aging demographics. I expect payroll growth to slow in the months ahead but the steady state of payrolls — at levels that do not raise the unemployment rate — will probably decline to a range of 50 – 75 thousand per month.
Developments around global trade, US federal outlays, and the federal workforce have weighed on business and consumer sentiment indicators, suggesting a deteriorating growth and inflation trade-off. The inflation expectations component of the most recent survey from the University of Michigan soared by the most since 1993, raising concerns about potential stagflation. However, the results appear to be politically biased, with Democratic respondents reporting much worse sentiment than Republicans. The misery index, 1 which combines the unemployment rate and inflation, remains well below levels that would raise alarm bells of a stagflationary environment, as actual measures of inflation (as opposed to survey-based) appear fairly well-anchored in the 3% range, still above the Fed’s 2% target.
The Fed announced a slower pace of the monthly reduction in its US Treasury securities holdings from US$25 billion to US$5 billion. Chair Powell highlighted some earlier disagreement among Committee members about the Fed’s balance-sheet policy, although it sounds like the reduction in pace was very broadly supported. Some considered it appropriate for the Fed to stay the course in winding down its balance-sheet runoff, or quantitative tightening (QT), while others advocated for a pause given potential disruptions from the debt ceiling. Liquidity conditions will likely get a boost with the slower pace of QT and potentially take some pressure off longer-term US Treasury yields. Chair Powell mentioned that the Fed is starting to see signs of tightness in money markets. There is some evidence to suggest that QT is contributing to the relative tightness of supply and demand conditions in the repo market, which makes interest rates more sensitive to changes in Treasury supply.
The change in QT should also ease financial conditions on the margin, which may be welcome to some market participants given the recent equity market sell-off and widening of credit spreads. However, this also threatens to add to existing upside inflation risks. I remain skeptical that the Fed will deliver on market expectations or its own projections for an additional two interest-rate cuts this year unless growth materially disappoints.
1The misery index was created by economist Arthur Okun in the 1970s as an indicator of economic health.
Expert
Rapid fire questions with Jeremy Butterworth on 2026 credit markets
Continue readingResilient growth, rising risks: Investing through the energy shock
Continue readingIncome investing in the Warsh Fed era: What investors should consider
Continue readingMultiple authors
European high yield: time for selectivity
Continue readingMultiple authors
September FOMC: Doves capitulate
Continue readingAI capex and the new credit cycle
Continue readingMultiple authors
Band-aids, bazookas, and boomerangs: Equity investing in a volatile US rate regime
Continue readingURL References
Related Insights
Rapid fire questions with Jeremy Butterworth on 2026 credit markets
Investment Strategist Jeremy Butterworth discusses why credit markets have remained resilient despite shifting rate expectations, where dispersion is creating opportunities for active investors, and why Asia continues to offer a compelling credit opportunity set.
Resilient growth, rising risks: Investing through the energy shock
Macro Strategist Eoin O’Callaghan explores the drivers of resilient growth amid the continued energy shock and discusses why investors need to keep a close eye on evolving macro conditions.
Income investing in the Warsh Fed era: What investors should consider
How should income investors be positioned for a Warsh-led Fed? Our experts believe it begins by rethinking fundamentals, and being more deliberate and adaptive.
Multiple authors
European high yield: time for selectivity
Portfolio Managers Konstantin Leidman and Thomas Kelly, and Investment Director Jennifer Martin discuss how European high-yield investors should rethink their approach in response to historically tight spreads.
Multiple authors
September FOMC: Doves capitulate
For the first time in over three years, the Fed raised the target rate range to 3.75%-4.00% in September. Our team looks at what's driving the shift and what it means going forward.
AI capex and the new credit cycle
Fixed Income Portfolio Managers Alyssa Irving and Liz Kleinerman, and Head of Investment Grade Private Credit Emeka Onukwugha explore the emergence of an AI investment cycle in credit markets.
Multiple authors
Band-aids, bazookas, and boomerangs: Equity investing in a volatile US rate regime
With fiscal pressures and Treasury-market fragilities keeping bond yields volatile, Macro Strategist Juhi Dhawan outlines implications for equity investors.
High asset prices, not low interest rates, are driving inflation
Wealth distribution in the US has rendered the Federal Reserve’s usual tools less effective. The Fed will need to address asset prices head-on in creative ways if it is going to return inflation to target.
By
How AI is impacting the high yield market
Fixed Income Portfolio Manager Blake Huynh examines how AI is reshaping the high-yield market using the latest issuance data. He explores what this transformation may mean for investors.
By
2026 midyear outlook: Time to rethink EM debt
Our expert argues that emerging market debt may merit a fresh look as stronger fundamentals, credible policymaking, and attractive yields challenge outdated assumptions about the asset class.
Warsh’s first FOMC: We have a task force for that
Our experts highlight new task forces, examine evolving inflation and labor dynamics, and contend that the Fed soon may need to choose between growth support and price stability.
URL References
Related Insights
Past results are not necessarily indicative of future results and an investment can lose value. Funds returns are shown net of fees. Source: Wellington Management
© 2026 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. The Overall Morningstar Rating for a fund is derived from a weighted average of the three, five, and ten year (if applicable) ratings, based on risk-adjusted return. Past performance is no guarantee of future results.
The content within this page is issued by Wellington Management Singapore Pte Ltd (UEN: 201415544E) (WMS). This advertisement or publication has not been reviewed by the Monetary Authority of Singapore. Information contained on this website is provided for information purposes and does not constitute financial advice or recommendation in any security including but not limited to, share in the funds and is prepared without regard to the specific objectives, financial situation or needs of any particular person.
Investment in the funds described on this website carries a substantial degree of risk and places an investor’s capital at risk. The price and value of investments is not guaranteed. The value of the shares of the funds and the income accruing to them, if any, and may fall or rise. An investor may not get back the original amount invested and an investor may lose all of their investment. Investment in the funds described on this website is not suitable for all investors. Investors should read the prospectus and the Product Highlights Sheet of the respective fund and seek financial advice before deciding whether to purchase shares in any fund. Past performance or any economic trends or forecast, are not necessarily indicative of future performance. Some of the funds described on this website may use or invest in financial derivative instruments for portfolio management and hedging purposes. Investments in the funds are subject to investment risks, including the possible loss of the principal amount invested. None of the funds listed on this website guarantees distributions and distributions may fluctuate and may be paid out of capital. Past distributions are not necessarily indicative of future trends, which may be lower. Please note that payment of distributions out of capital effectively amounts to a return or withdrawal of the principal amount invested or of net capital gains attributable to that principal amount. Actual distribution of income, net capital gains and/or capital will be at the manager’s absolute discretion. Payments on dividends may result in a reduction of NAV per share of the funds. The preceding paragraph is only applicable if the fund intends to pay dividends/ distributions. Performance with preliminary charge (sales charge) is calculated on a NAV to NAV basis, net of 5% preliminary charge (initial sales charge). Unless stated otherwise data is as at previous month end.
Subscriptions may only be made on the basis of the latest prospectus and Product Highlights Sheet, and they can be obtained from WMS or fund distributors upon request.
This material may not be reproduced or distributed, in whole or in part, without the express written consent of Wellington Management.
We seek to exceed the investment objectives and service expectations of our fund investors and their advisers worldwide
© Copyright 2026 Wellington Management Singapore Pte. Ltd. All rights reserved.
WELLINGTON MANAGEMENT FUNDS ® is a registered service mark of Wellington Group Holdings LLP.
Wellington Management Singapore Pte. Ltd., a private limited company incorporated in the Republic of Singapore. Address: 8 Marina Boulevard, Tower 1 #03-01 Marina Bay Financial Centre 018981. Licensed and regulated by the Monetary Authority of Singapore.