- Fixed Income Portfolio Manager
Skip to main content
- Funds
- Capabilities
- Insights
- About Us
FEATURED EQUITY FUNDS
FEATURED FIXED INCOME FUNDS
Asset classes
Singapore, Individual
Changechevron_rightFEATURED EQUITY FUNDS
FEATURED FIXED INCOME FUNDS
Asset classes
The views expressed are those of the authors at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed.
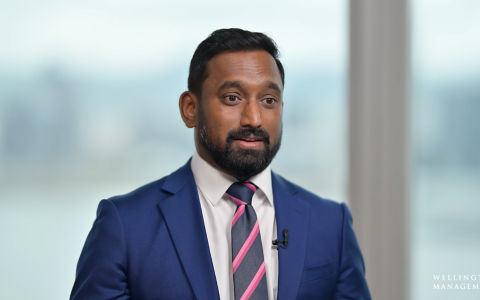
Paul Skinner, discusses the US election results and the implications for the bond market with Fixed income Portfolio Manager Connor Fitzgerald. Below is a transcript of the interview.
Paul Skinner: It's the day after the US election and we have the result. Fortunately, I have Connor Fitzgerald here with me who is from Boston, and he hopefully can shed a little bit of light on what has gone on. Connor, were you surprised by the Trump result?
Connor Fitzgerald: I would say we're a little bit surprised in terms of the margin of victory, for sure. I think our view going into the election, it was going to be really tight, looking like a toss-up. Happy to talk about some of the market implications and how we’re positioning.
Paul Skinner: That's key. How were you positioned going in, if you were 50-50? And what do you think you’re going to do as you go forth?
Connor Fitzgerald: Sure, going in, we've had this view that on a longer-term structural basis, the fiscal deficits in the US are definitely a concern. We didn't think that was going to change regardless of who won the presidency, or the House or the Senate. If anything, we think there is a risk that a Trump administration — depending on how much of a win they have in the Republican Senate or in the House – we think it does pull forward those fiscal issues, and we think that's important for the bond market.
Going into this week, we've been favoring positioning in on the Treasury curve. Owning shorter maturity securities and trying to keep our duration down, thinking that a Trump victory would lead to a steepening of the Treasury curve. We've definitely seen that play out in the past couple of weeks as his odds move higher and have continued to see it this morning. But we still think on a longer-term structural horizon, there's still scope for the yield curve to steepen and that's driven by a couple of things. Regardless of how they do in the House and the Senate, we think he can make moves on immigration, which we think is inflationary, make moves on tariffs which is also inflationary, deregulation, pro-growth... Most of his policies, we think, are pro-growth and pro-inflation for the immediate investable time horizon. That's what we are focused on and why we're keeping the duration down.
Paul Skinner: Ok, so duration down. What about your position in risk assets? How are you looking at credit as we go through?
Connor Fitzgerald: Credit spreads have run a lot this year, and even just in the past month, have moved tighter by a pretty significant amount. We still think it's a pretty good time to be invested in credit, but we do want to acknowledge the valuation equation is not as good as it was at the beginning of the year. Frankly, I would say there's probably more upside in equities at this point, as we're sort of later in the spread cycle. But I think there are still some good, idiosyncratic opportunities in different sectors, high yield, and sectors in emerging markets. The overall yield equation still looks pretty good in fixed income to earn some income without taking a ton of credit risk, or a ton of duration.
Paul Skinner: So, that duration credit all looks sensible, but we got a Trump presidency. What could go wrong? What are the risks in both those areas?
Connor Fitzgerald: I think a lot of his policies are kind of challenge-the-status-quo. He could get really aggressive on tariffs. He's talked about having his administration be involved with the Federal Reserve decision-making process. He's obviously pro-American business and onshoring, which is going to potentially accelerate the deglobalization theme, fragmented supply chains, etc.
I would say the biggest risk is the back end of the Treasury curve. I don't want to say it becomes unanchored, but it just becomes more volatile. So that's definitely something we're focused on as we get an idea of what he plans to do in his first 60 to 90 days.
Paul Skinner: Okay, and do you think there's going to be a lot of activity in that early stage? Or will you wait for them to do a calculated move on these various things, like tariffs?
Connor Fitzgerald: I think it will be calculated, but I think he's been pretty clear on what he wants to do. So, I think he'll get going pretty quickly.
Paul Skinner: Excellent, all right. We'll look forward to the market implications, and we'll definitely be talking to you again. Thank you, Connor.
Experts
Related funds
Wellington Credit Total Return Fund
A long-only cash and bond fund seeking long-term total returns by investing primarily in US Dollar-denominated treasuries, corporate bonds and emerging markets issuers.
Rapid fire questions with Jeremy Butterworth on 2026 credit markets
Continue readingResilient growth, rising risks: Investing through the energy shock
Continue readingIncome investing in the Warsh Fed era: What investors should consider
Continue readingMultiple authors
European high yield: time for selectivity
Continue readingMultiple authors
September FOMC: Doves capitulate
Continue readingAI capex and the new credit cycle
Continue readingMultiple authors
Band-aids, bazookas, and boomerangs: Equity investing in a volatile US rate regime
Continue readingURL References
Related Insights
Rapid fire questions with Jeremy Butterworth on 2026 credit markets
Investment Strategist Jeremy Butterworth discusses why credit markets have remained resilient despite shifting rate expectations, where dispersion is creating opportunities for active investors, and why Asia continues to offer a compelling credit opportunity set.
Resilient growth, rising risks: Investing through the energy shock
Macro Strategist Eoin O’Callaghan explores the drivers of resilient growth amid the continued energy shock and discusses why investors need to keep a close eye on evolving macro conditions.
Income investing in the Warsh Fed era: What investors should consider
How should income investors be positioned for a Warsh-led Fed? Our experts believe it begins by rethinking fundamentals, and being more deliberate and adaptive.
Multiple authors
European high yield: time for selectivity
Portfolio Managers Konstantin Leidman and Thomas Kelly, and Investment Director Jennifer Martin discuss how European high-yield investors should rethink their approach in response to historically tight spreads.
Multiple authors
September FOMC: Doves capitulate
For the first time in over three years, the Fed raised the target rate range to 3.75%-4.00% in September. Our team looks at what's driving the shift and what it means going forward.
AI capex and the new credit cycle
Fixed Income Portfolio Managers Alyssa Irving and Liz Kleinerman, and Head of Investment Grade Private Credit Emeka Onukwugha explore the emergence of an AI investment cycle in credit markets.
Multiple authors
Band-aids, bazookas, and boomerangs: Equity investing in a volatile US rate regime
With fiscal pressures and Treasury-market fragilities keeping bond yields volatile, Macro Strategist Juhi Dhawan outlines implications for equity investors.
High asset prices, not low interest rates, are driving inflation
Wealth distribution in the US has rendered the Federal Reserve’s usual tools less effective. The Fed will need to address asset prices head-on in creative ways if it is going to return inflation to target.
By
How AI is impacting the high yield market
Fixed Income Portfolio Manager Blake Huynh examines how AI is reshaping the high-yield market using the latest issuance data. He explores what this transformation may mean for investors.
By
2026 midyear outlook: Time to rethink EM debt
Our expert argues that emerging market debt may merit a fresh look as stronger fundamentals, credible policymaking, and attractive yields challenge outdated assumptions about the asset class.
Warsh’s first FOMC: We have a task force for that
Our experts highlight new task forces, examine evolving inflation and labor dynamics, and contend that the Fed soon may need to choose between growth support and price stability.
URL References
Related Insights
Past results are not necessarily indicative of future results and an investment can lose value. Funds returns are shown net of fees. Source: Wellington Management
© 2026 Morningstar, Inc. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar nor its content providers are responsible for any damages or losses arising from any use of this information. The Overall Morningstar Rating for a fund is derived from a weighted average of the three, five, and ten year (if applicable) ratings, based on risk-adjusted return. Past performance is no guarantee of future results.
The content within this page is issued by Wellington Management Singapore Pte Ltd (UEN: 201415544E) (WMS). This advertisement or publication has not been reviewed by the Monetary Authority of Singapore. Information contained on this website is provided for information purposes and does not constitute financial advice or recommendation in any security including but not limited to, share in the funds and is prepared without regard to the specific objectives, financial situation or needs of any particular person.
Investment in the funds described on this website carries a substantial degree of risk and places an investor’s capital at risk. The price and value of investments is not guaranteed. The value of the shares of the funds and the income accruing to them, if any, and may fall or rise. An investor may not get back the original amount invested and an investor may lose all of their investment. Investment in the funds described on this website is not suitable for all investors. Investors should read the prospectus and the Product Highlights Sheet of the respective fund and seek financial advice before deciding whether to purchase shares in any fund. Past performance or any economic trends or forecast, are not necessarily indicative of future performance. Some of the funds described on this website may use or invest in financial derivative instruments for portfolio management and hedging purposes. Investments in the funds are subject to investment risks, including the possible loss of the principal amount invested. None of the funds listed on this website guarantees distributions and distributions may fluctuate and may be paid out of capital. Past distributions are not necessarily indicative of future trends, which may be lower. Please note that payment of distributions out of capital effectively amounts to a return or withdrawal of the principal amount invested or of net capital gains attributable to that principal amount. Actual distribution of income, net capital gains and/or capital will be at the manager’s absolute discretion. Payments on dividends may result in a reduction of NAV per share of the funds. The preceding paragraph is only applicable if the fund intends to pay dividends/ distributions. Performance with preliminary charge (sales charge) is calculated on a NAV to NAV basis, net of 5% preliminary charge (initial sales charge). Unless stated otherwise data is as at previous month end.
Subscriptions may only be made on the basis of the latest prospectus and Product Highlights Sheet, and they can be obtained from WMS or fund distributors upon request.
This material may not be reproduced or distributed, in whole or in part, without the express written consent of Wellington Management.
We seek to exceed the investment objectives and service expectations of our fund investors and their advisers worldwide
© Copyright 2026 Wellington Management Singapore Pte. Ltd. All rights reserved.
WELLINGTON MANAGEMENT FUNDS ® is a registered service mark of Wellington Group Holdings LLP.
Wellington Management Singapore Pte. Ltd., a private limited company incorporated in the Republic of Singapore. Address: 8 Marina Boulevard, Tower 1 #03-01 Marina Bay Financial Centre 018981. Licensed and regulated by the Monetary Authority of Singapore.