
- Equity Strategist
United States, Institutional
Change
This is an excerpt from our Investment Outlook, in which specialists from across our investment platform share insights on the economic and market forces that we expect to influence portfolios.
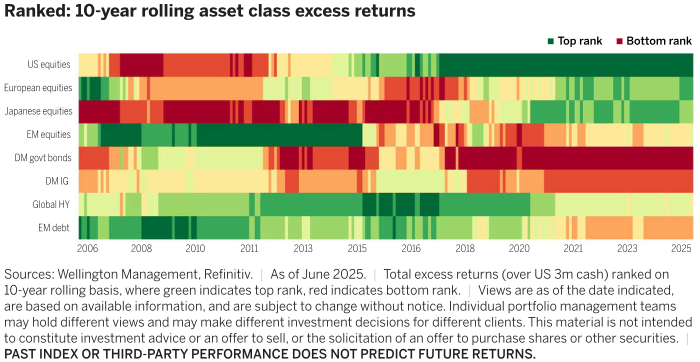
Over the last 15 years, US public companies have achieved superior performance and faster growth than the rest of the world, while also nearly systematically exceeding absolute return expectations. Coupled with favorable starting valuations, these tailwinds have delivered a prolonged period of exceptional returns for US equities, well ahead of other asset classes and markets (Figure 1). For non-US investors, these returns were further enhanced by a consistently strengthening dollar. Now, with valuations at much higher levels and growing doubts about the US’s global leadership, investors have started to ask if this US exceptionalism can persist.
Figure 1
Yet, as we look to the second half of 2026, perhaps the more accurate question to ask is not whether, but how US exceptionalism might evolve? And what can investors do to prepare? The first half of the year offers us some indication. Here we share a few observations.
With the world shifting from multilateralism to unilateralism, dispersion has returned
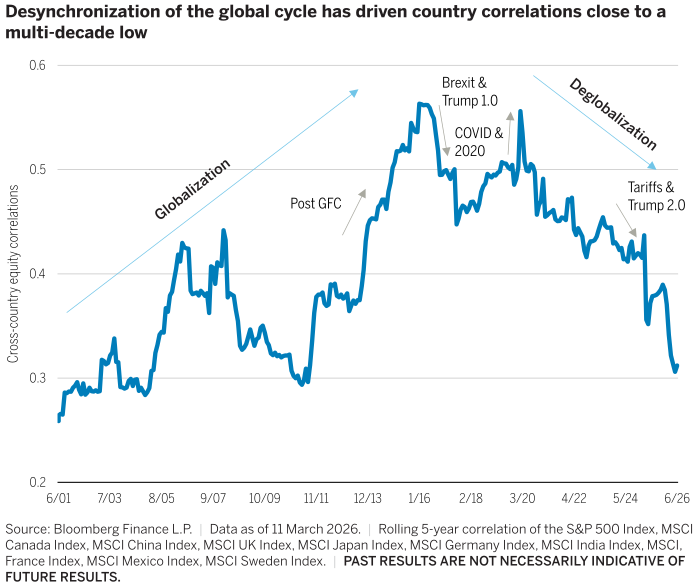
The prior economic regime of expanding globalization was characterized by synchronized global growth, high correlations in economic cycles and equity markets, low dispersion, low inflation, and falling interest rates. In a highly synchronized environment, investors were incentivized to reduce diversification and concentrate exposure into whichever asset class (or market) was delivering the best growth. During this period, anything an investor did to hedge or diversify away from the US equity market or the US dollar generally increased volatility and lowered returns. But as Figure 2 illustrates, global markets are no longer moving together in the same way. The correlation of global equity markets rose steadily from 2000 to hit a peak in 2016 — a period that in retrospect has come to signal the beginning of the fracturing of globalization. The desynchronization of the global cycle has now driven country correlations close to a multi-decade low.
Figure 2
The starting point for valuations does matter
The US equity market today is very different than it was 50 years ago. Then, capital-intensive manufacturing and industrial sectors were the beating heart of the American equity market. When the capital-light tech sector took off, the runway for growth increased exponentially, helping to fuel US exceptionalism. But now, the rapid growth in AI-related capital expenditure is drawing into question the future returns on this invested capital.
Moreover, US equities have historically earned their higher valuations through consistently delivering faster growth and outcomes that beat expectations. Now, valuations imply a bigger hurdle for future beats at a time when the positioning of the US relative to the rest of the world may be changing, while, overall, US earnings expectations remain at a multiyear high.
The US is increasingly not the only AI game in town
Exceptional US companies may continue to excel, but in this nascent stage of AI, we see plenty of room for new competitors — in the US and elsewhere — to grow, succeed, and even displace incumbents. Prudent investors will look for opportunities among new and established companies alike, both in historically dominant markets, like the US, and in others, like Asia, where innovative, new AI-focused companies have long runways to thrive.
It’s worth underscoring that while US megacap technology companies dominate the application and platform layer of AI, Asia plays a critical role in enabling the infrastructure behind it, and the region’s role in the semiconductor ecosystem serves as a good example. The region holds leading positions in materials, memory, and advanced manufacturing capabilities that we think are difficult to replicate at scale. Japan owns a significant proportion of the critical materials and tools, Korea leads memory, and Taiwan still sets the bar in advanced fabrication and packaging.
Earnings growth continues to broaden, even outside of AI-driven growth
While for the most part today’s US market leaders are still expected to deliver superior growth, especially in the broader tech space, there are reasons to look elsewhere, both in the US and beyond. Against a backdrop of stronger-than-anticipated economic growth and ongoing fiscal support, we continue to see signs of a broadening in earnings growth across sectors, market cap, and regions. This points to the potential for a wider set of beneficiaries, suggesting that investors may wish to position for more diversified sources of growth.
The US dollar remains in a tenuous position
One of the major factors supporting US exceptionalism has been a consistently strengthening currency, delivering not just enhanced returns but also “risk off” diversification benefits. This trend of persistent dollar strength has now come to an end as evidenced by the significant weakening we saw prior to the US-Iran conflict. Since then, the dollar has rallied somewhat but, longer term, it remains vulnerable to growing uncertainty about the US’s long-term fiscal position and the role of the dollar as the world’s reserve currency. The attractiveness of the dollar may be further undermined if investors start to view it as a source of risk amplification rather than risk mitigation.
US policy actions continue to drive “reflexive” responses from the rest of the world
Political drivers and objectives are now shaping economic decisions. This means investors increasingly need to look at the direction policymakers are headed in order to understand risks and opportunities.
As US policies shift away from the prior global order, other countries may have reflexive responses that could encourage their own domestic resilience and economic strength. Over time, this could narrow the gap for US growth expectations relative to the rest of the world.
Europe and Japan in particular appear to be stepping up efforts to insulate their economies from external shocks. After decades of relying on external demand, imported energy, and US-provided security, these regions are now reassessing the sustainability of that model. First, both are net energy importers and are likely to accelerate efforts to reduce reliance on fossil fuel imports. Second, Europe and Japan have historically relied not only on the US security umbrella but also on US defense technology. With future US support less certain, domestic defense capabilities are likely to become a greater priority. And finally, as major beneficiaries of globalization, both regions have long depended on exports. However, with China exporting excess capacity and the US raising trade barriers, we are likely to see an increased focus on boosting domestic demand and protecting local industries to offset external headwinds.
In our view, these regime shifts in both Europe and Japan could create winners and losers, potentially expanding the opportunity set for active managers. Moreover, European and Japanese equities are likely to offer improved diversification as their drivers increasingly decouple from the US cycle.
The problem equity investors face now is how to deal with a world in which US exceptionalism appears to be both intact and waning. An 80-year history of US economic, geopolitical, and military dominance — one that’s driven dollar primacy, powered US financial markets and, for the most part, supported global stability — is being challenged. While most of these dynamics still hold, it’s also true that the world and the US face growing turbulence in many forms: expanding regional conflicts, economic instability, and diminishing policy cohesion. The effects of this emerging dichotomy on capital markets are beginning to take shape, and asset allocators need to understand what the two truths of US exceptionalism — namely, it still holds and it’s waning — may mean for them.
Because we believe US exceptionalism remains largely intact, investors should stay invested in US equities but potentially look to broaden their exposure. However, we think that they should also be prepared to accept lower risk-adjusted returns relative to what they’ve grown accustomed to in the last 15 years, but also compared to the rest of the world, especially given high starting valuations. And because US exceptionalism is simultaneously waning, we also believe investors should balance investment in the US with increased allocations to non-US markets, both to effectively diversify US exposure and add to the potential for higher risk-adjusted returns.
Wellington Management Company LLP (WMC) is an independently owned investment adviser registered with the US Securities and Exchange Commission (SEC). WMC is also registered with the US Commodity Futures Trading Commission (CFTC) as a commodity trading advisor (CTA) and commodity pool operator (CPO). WMC serves as a CTA to certain clients including commodity pools operated by registered commodity pool operators. WMC provides commodity trading advice to all other clients in reliance on exemptions from CTA registration. WMC serves as a CPO to certain Wellington sponsored pooled vehicles. WMC, along with its affiliates (collectively, Wellington Management), provides investment management and investment advisory services to institutions around the world. Wellington Management Group LLP (WMG), a Massachusetts limited liability partnership, serves as the ultimate parent holding company of the Wellington Management global organization. All of the partners are full-time professional members of Wellington Management. Located in Boston, Massachusetts, Wellington Management also has offices in Chicago, Illinois; New York, New York; Radnor, Pennsylvania; San Francisco, California; DIFC, Dubai; Frankfurt; Hong Kong; London; Luxembourg; Madrid; Milan; Shanghai; Singapore; Sydney; Tokyo; Toronto; and Zurich.
This material is prepared for, and authorized for internal use by, designated institutional and professional investors and their consultants or for such other use as may be authorized by Wellington Management. This material and/or its contents are current at the time of writing and may not be reproduced or distributed in whole or in part, for any purpose, without the express written consent of Wellington Management. This material is not intended to constitute investment advice or an offer to sell, or the solicitation of an offer to purchase shares or other securities. Investors should always obtain and read an up-to-date investment services description or prospectus before deciding whether to appoint an investment manager or to invest in a fund. Any views expressed herein are those of the author(s), are based on available information, and are subject to change without notice. Individual portfolio management teams may hold different views and may make different investment decisions for different clients. While any third-party data used is considered reliable, its accuracy is not guaranteed. Forward-looking statements should not be considered as guarantees or predictions of future events. Past results are not a reliable indicator of future results. Wellington assumes no duty to update any information in this material in the event that such information changes.
In Canada, this material is provided by Wellington Management Canada ULC, a British Columbia unlimited liability company registered in the provinces of Alberta, British Columbia, Manitoba, New Brunswick, Newfoundland and Labrador, Nova Scotia, Ontario, Prince Edward Island, Quebec, and Saskatchewan in the categories of Portfolio Manager and Exempt Market Dealer.
In Europe (excluding the United Kingdom and Switzerland), this material is provided by the marketing entity Wellington Management Europe GmbH (WME) which is authorized and regulated by the German Federal Financial Supervisory Authority (Bundesanstalt für Finanzdienstleistungsaufsicht – BaFin). This material may only be used in countries where WME is duly authorized to operate and is only directed at eligible counterparties or professional clients as defined under the German Securities Trading Act. This material does not constitute investment advice, a solicitation to invest in financial instruments or information recommending or suggesting an investment strategy within the meaning of Section 85 of the German Securities Trading Act (Wertpapierhandelsgesetz).
In the United Kingdom, this material is provided by Wellington Management International Limited (WMIL), a firm authorized and regulated by the Financial Conduct Authority (FCA) in the UK (Reference number: 208573). This material is directed only at eligible counterparties or professional clients as defined under the rules of the FCA.
In Switzerland, this material is provided by Wellington Management Switzerland GmbH, a firm registered at the commercial register of the canton of Zurich with number CH-020.4.050.857-7. This material is directed only at Qualified Investors as defined in the Swiss Collective Investment Schemes Act and its implementing ordinance.
In Dubai, this material is provided by Wellington Management (DIFC) Limited (WM DIFC), a firm registered in the DIFC with number 7181 and regulated by the Dubai Financial Services Authority (“DFSA”). To the extent this document relates to a financial product, such financial product is not subject to any form of regulation or approval by the DFSA. The DFSA has no responsibility for reviewing or verifying any prospectus or other documents in connection with any financial product to which this document may relate. The DFSA has not approved this document or any other associated documents nor taken any steps to verify the information set out in this document, and has no responsibility for it. Any financial product to which this document relates may be illiquid and/or subject to restrictions on its resale. Prospective purchasers should conduct their own due diligence on any such financial product. If you do not understand the contents of this document you should consult an authorised financial adviser. This document is provided on the basis that you are a Professional Client and that you will not copy, distribute or otherwise make this material available to any person.
In Hong Kong, this material is provided to you by Wellington Management Hong Kong Limited (WM Hong Kong), a corporation licensed by the Securities and Futures Commission to conduct Type 1 (dealing in securities), Type 2 (dealing in futures contracts), Type 4 (advising on securities), and Type 9 (asset management) regulated activities. By accepting this material you acknowledge and agree that this material is provided for your use only and that you will not distribute or otherwise make this material available to any person.
Wellington Private Fund Management (Shanghai) Limited (WPFM), which is an unregulated entity incorporated in China, is a wholly-owned subsidiary of WM Hong Kong. Wellington Global Private Fund Management (Shanghai) Limited (WGPFM) is a wholly-owned entity and subsidiary of WPFM and is registered as a private fund manager with Asset Management Association of China to conduct qualified domestic limited partnership and management activities. In mainland China, this material is provided for your use by WPFM, WGPFM, or WMHK (as the case may be).
In Singapore, this material is provided for your use only by Wellington Management Singapore Pte Ltd (WM Singapore) (Registration Number 201415544E). WM Singapore is regulated by the Monetary Authority of Singapore under a Capital Markets Services Licence to conduct fund management activities and deal in capital markets products, and is an exempt financial adviser. By accepting this material you represent that you are a non-retail investor and that you will not copy, distribute or otherwise make this material available to any person.
In Australia, Wellington Management Australia Pty Ltd (WM Australia) (ABN 19 167 091 090) has authorized the issue of this material for use solely by wholesale clients (as defined in the Corporations Act 2001). By accepting this material, you acknowledge and agree that this material is provided for your use only and that you will not distribute or otherwise make this material available to any person.
In Japan, Wellington Management Japan Pte Ltd (WM Japan) (Registration Number 199504987R) has been registered as a Financial Instruments Firm with registered number: Director General of Kanto Local Finance Bureau (Kin-Sho) Number 428. WM Japan is a member of the Investment Management Association of Japan (IMAJ) and the Type II Financial Instruments Firms Association (T2FIFA).
WM Hong Kong and WM Japan are also registered as investment advisers with the SEC; however, they will comply with the substantive provisions of the US Investment Advisers Act only with respect to their US clients.
©2026 Wellington Management Company LLP. All rights reserved.
The views expressed are those of the authors at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.
Experts




Monthly Market Review — August 2026
A monthly update on equity, fixed income, currency, and commodity markets.
By