Overview
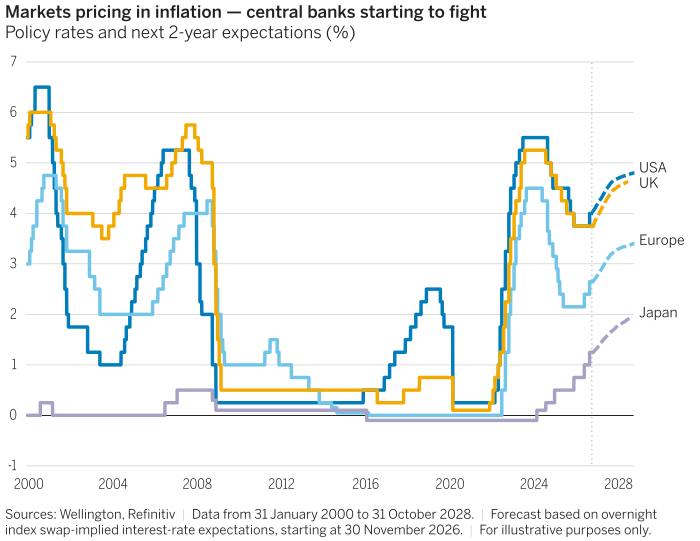
The macro backdrop has become more demanding for investors. Bond yields have risen sharply as stubborn inflation, higher energy prices, and government debt concerns have driven hawkish monetary policy expectations.
At the same time, enthusiasm around AI has continued to support investment, anticipated productivity gains, and corporate earnings. Together, these forces have helped sustain the equity rally even in the face of higher rates.
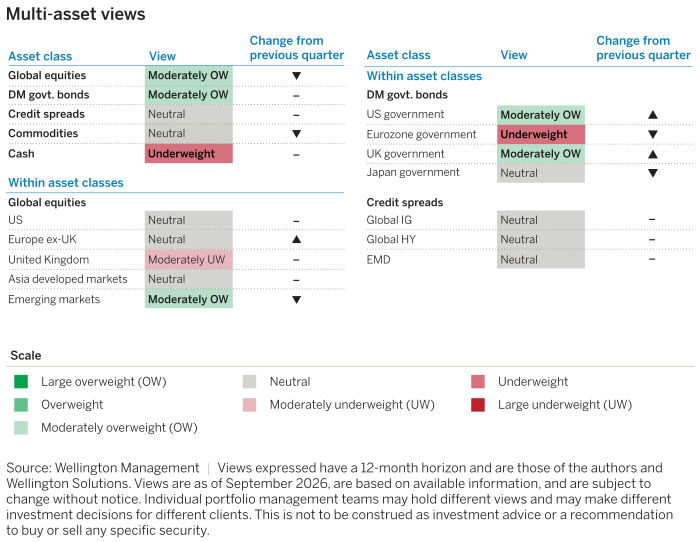
Looking ahead over the next 12 months, we remain broadly constructive but less emphatically so. We think the balance of risks has weakened, prompting us to temper equity exposure while finding more value in government bonds. In this quarter’s outlook, we consider where the rally may still have room to run — and where rising yields, market concentration, and other forces may call for selectivity.
Equities
We have pared back our view on global equities from overweight to moderately overweight. Despite exceptional second-quarter earnings, continued support from AI infrastructure spending, and healthy earnings breadth, the near-term risk/reward trade-off has deteriorated. The bar for upside surprises in earnings is now much higher, and the speed and level of the rise in yields present some risks.
We remain largely positive on the AI capex cycle and its impact on earnings, with demand for compute still far outstripping supply. That said, we recognize that earnings have been running above trend and expect their exceptionally strong growth rates to decelerate.
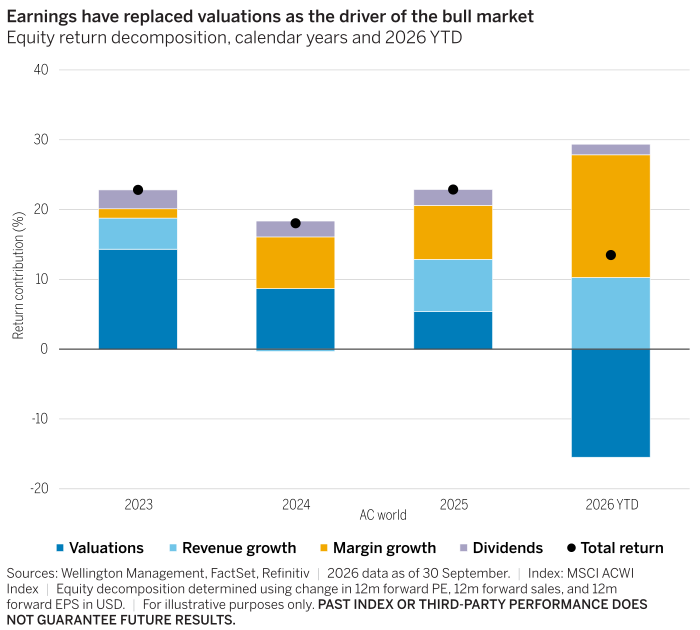
One concern is that while earning growth has broadened, market breadth has deteriorated. Market concentration in AI-related stocks, which are exposed to a potentially cyclical capital-spending boom, is driving a reluctance to assume current earnings expectations will be fully realized. Together with higher rates, these concerns have driven a contraction of approximately 15% in global equity valuation multiples this year (Figure 1).