
-
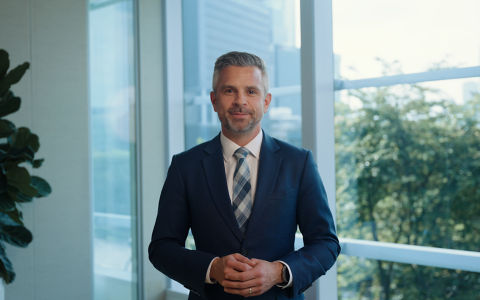
Andrew Sharp Paul
- Solutions Director, APAC
Explore our insights
Asset class
Formats
2026 Midyear Investment Outlook

2026 Midyear Investment Outlook
Watch Solutions Director Andrew Sharp Paul share three portfolio ideas for the second half of 2026, with a focus on quality equities, flexible fixed income, and diversifiers that may help build portfolio resilience.
Recent volatility, be it from tech-led swings to renewed uncertainty around inflation, once again reminds us that rallies can become fragile when gains are concentrated in a narrow group of leaders and amplified by a complicated macroeconomic backdrop.
While continued earnings strength is supporting meaningful opportunities, factors like diverging policy paths and elevated geopolitical risks are contributing to a wider range of possible market outcomes. As we look at the rest of the year, portfolio design has become more important, and three practical priorities matter most: focus, flexibility and resilience.
First, focus on where you are taking active risks, and be aware of any concentration in stocks dominating market momentum. In a market increasingly driven by themes or macroeconomic events, leadership can change quickly and headlines can create whipsaw risk. This reinforces the importance of remaining focused on areas where skill, fundamentals and opportunities are most aligned. That's why we believe higher quality companies remain compelling. Asian quality equities, in particular, if managed in a disciplined way, can offer exposure to attractive growth opportunities with downside mitigation potential.
Second, be flexible in how you manage your portfolio risks and your portfolio opportunities. A more volatile world is likely to reward investors who can be nimble. Within fixed income, leadership can shift quickly and no single sector can outperform at all times. Rotational strategies with the ability to move across sectors, credit qualities, and duration can help improve risk-adjusted return potential.
Third, build resilience into your portfolio deliberately. Traditional diversifiers have become less reliable in a world shaped by inflation shocks, policy uncertainty, and geopolitical change. This is where regime-aware diversifiers can play a more meaningful role. Hedge funds or liquid alternatives can offer differentiated return drivers with less dependence on broad market direction. While commodities may play a more structural role when inflation, supply shocks, or geopolitical stress are shaping the backdrop.
In a less predictable world, there is no single path forward. But by focusing on quality to capture equity alpha, being flexible in fixed income markets, and diversifying with alternatives to build resilience, investors can navigate the next phase of the cycle with greater confidence.
Discover more in our midyear outlook.
The views expressed are those of the speaker at the time of filming. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional, or accredited investors only.