- Insights
- Capabilities
- About Us
- My Account
Asia ex-Japan, Institutional
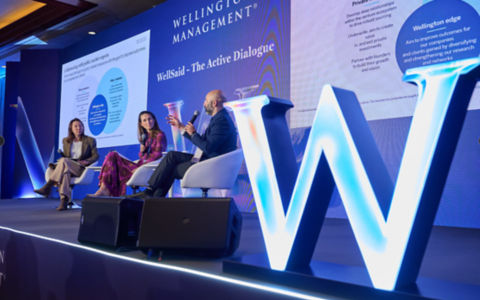
Changechevron_rightHosted in four cities, we were pleased to conclude another successful year of “WellSaid – The Active Dialogue”, our annual flagship outlook series across Hong Kong, Singapore, Bangkok and Kuala Lumpur.
We welcomed hundreds of institutional and wealth clients for active dialogues on portfolio construction, fixed income, equities, hedge funds, and private markets, all grounded in the mosaic of unique perspectives that underpins Wellington’s investment excellence.
The morning sessions in Hong Kong and Singapore hosted institutional clients for in-depth discussions on the multi-asset outlook and portfolio construction. The dialogue underscored the importance of multi-dimensional diversification and the role of dynamic risk management in today’s environment.
Meanwhile, the luncheon sessions brought together institutional and wealth clients for conversations on fixed income, equities, hedge funds, and private markets.
From navigating fixed income landscape to identifying top equity ideas and unpacking alternatives themes, the discussions reflected the breadth and depth of insights across our platform, helping clients bring the full picture into focus.
Thank you to our clients, speakers, and colleagues for making WellSaid 2026 a true reflection of the “active dialogue” we aim to foster. As we celebrate 30 years in APAC this year, we look forward to continuing our role as a trusted thought partner.
The views expressed are those of the speakers at the time of filming. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional, or accredited investors only.
Read more from our experts
Focus, flexibility and resilience:
Three portfolio ideas for 2H 2026
Watch Solutions Director Andrew Sharp Paul share three portfolio ideas for the second half of 2026, with a focus on quality equities, flexible fixed income, and diversifiers that may help build portfolio resilience.
2026 midyear outlook: Time to rethink EM debt
Our expert argues that emerging market debt may merit a fresh look as stronger fundamentals, credible policymaking, and attractive yields challenge outdated assumptions about the asset class.
What investors should watch as private credit market matures
Private credit is entering a more mature phase, marked by greater selectivity, broader opportunities, deeper market infrastructure, and growing emphasis on manager selection.
The rally and the reality
Can the markets remain resilient in the face of geopolitical disruption and inflation worries? We offer our views on the macro environment, AI-driven earnings, and the implications for equities, bonds, and commodities.
Looking beyond mega-caps
We explore how the growing concentration of capital in mega-cap private companies is reshaping the venture and growth opportunity set, and the implications for portfolio construction, manager selection, diversification, and potential return opportunities across private markets.
Growth outlook faces a new test: Inflation
Explore our latest views on risks and opportunities across global capital markets.
Preparing for a shift in US exceptionalism
Equity Strategist Andrew Heiskell and Macro Strategist Nicolas Wylenzek explore the evolving nature of US exceptionalism in their 2026 midyear equity outlook.
Three priorities for investors in a less predictable world
Despite adverse headlines and events, risk markets have remained constructive this year, but the rally has become increasingly dependent on a limited set of market leaders. How robust can markets be when so much depends on momentum continuing unchecked?
Tighter spreads, wider dispersion
Fixed Income Portfolio Managers Campe Goodman and Rob Burn share their midyear outlook for credit markets. They find that tight index spreads do not mean a lack of opportunity.
No rerun of the 2022 rates scenario but flexibility is key
Fixed Income Portfolio Manager Martin Harvey and Investment Director Marco Giordano share their outlook for rates (government bonds) for the second half of the year.
Markets are underestimating the persistence of inflation
Macro Strategists Eoin O'Callaghan, Michael Medeiros and John Butler share their macro outlook for the remainder of 2026 and discuss the implications of the ongoing energy shock for markets and investors.
URL References
Related Insights
© Copyright 2026 Wellington Management Company LLP. All rights reserved. WELLINGTON MANAGEMENT ® is a registered service mark of Wellington Group Holdings LLP. For institutional or professional investors only.