Australia & NZ, Institutional
Change

Oil prices have put the Federal Reserve (Fed) back in focus. But for investors, the bigger question is no longer simply whether higher energy prices lead to another rate hike.
The oil shock is colliding with several forces that could keep inflation and long-term rates under pressure: supply-chain fragmentation, fiscal deficits, deglobalization, and the enormous amount of capital needed to fund AI and infrastructure.
Together, they point to a broader challenge: The forces setting the cost of capital are multiplying, and traditional sources of diversification may not respond to them as they have in the past.
Oil is the catalyst, not the whole story
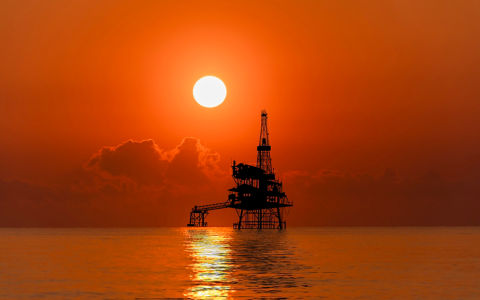
The closure of the Strait of Hormuz disrupted a waterway that normally carries roughly one-fifth of the world’s seaborne oil trade. The situation became more difficult after Saudi Arabia shut its East-West Pipeline following a drone attack. That pipeline had been moving roughly 4-5 million barrels per day and provided a major route for Saudi crude to bypass Hormuz.
Against that backdrop, Brent crude was trading around US$107–US$109 on September 14, after sitting below US$70 as recently as June.
The bigger issue is not simply that oil prices are higher. Markets increasingly must consider whether meaningful normalization arrives at all in 2026.
Oil shocks are especially difficult for central banks because higher rates cannot fix the underlying supply problem. Higher rates can cool demand, but they can’t reopen shipping lanes, repair damaged infrastructure, reduce tanker insurance costs, or create more oil.
That leaves the Fed with an uncomfortable trade-off: Higher energy prices can slow growth while pushing inflation higher.
The inflation question is now pass-through
The latest inflation data shows the first-order effect. Consumer prices rose 0.4% in August and 3.4% over the past year. Energy prices rose 2.1% during the month, while gasoline rose 3.9% and accounted for more than one-third of the monthly increase.
Core inflation was considerably calmer, at 2.4% year over year.
That distinction matters. If oil prices fall relatively quickly, much of the inflation impact could remain concentrated in headline inflation and eventually fade.
The greater risk is that higher oil and diesel prices work their way into freight, air travel, manufacturing, agriculture, and other input costs. If businesses begin passing those costs through and households and markets start expecting inflation to remain higher, the policy problem becomes more difficult.
The US economy is more energy efficient and a much larger oil producer than it was during the oil shocks of the 1970s, which may reduce the damage from a given move in oil.
But resilience can cut both ways. If growth and employment hold up while inflation stays elevated, the Fed may have more reason to remain focused on inflation.
Long-term rates are telling a second story
Fed policy is only part of the rates picture. The 10-year Treasury yield briefly reached 5% in mid-September, as markets demanded more compensation for inflation and duration risk. At current bond yield levels, the 10-year Treasury would need to rise past 5.5% for investors to lose money in the next year. In other words, bonds offer a margin of safety, but only if investors are willing to expand their time horizons.
Long-term yields reflect inflation expectations, Treasury supply, the premium investors demand for holding long-dated bonds, and competition for capital from private investment.
That last factor is becoming increasingly important. Data centers, power generation, grid investment, and other infrastructure associated with AI require enormous amounts of capital.
AI, then, isn’t just an equity story but a cost-of-capital story.
A cash-rich technology company funding investment from its own balance sheet is in a very different position from a developer dependent on repeated access to private credit or project finance.
For equity investors, the question is whether companies can earn returns on that spending above a higher cost of capital. For credit investors, cash flow, collateral, leverage, and financing flexibility become critical.
The AI opportunity may reward selection as much as exposure.
Why traditional diversification may need reinforcements
For much of the period following the global financial crisis, portfolios benefited from a familiar pattern: Growth weakened, inflation fell, the Fed eased, yields declined, and bonds helped offset equity weakness.
A supply-driven inflation shock can look different.
Inflation may rise even as growth becomes less certain. The Fed may remain restrictive, while long-term yields stay elevated or move higher.
That can put pressure on equities through higher discount rates and weaker margins at the same time nominal bonds are hurt by rising yields.
This doesn’t mean bonds have entirely stopped diversifying equities. In a conventional growth slowdown, long Treasuries may still provide useful protection.
But it does mean diversification may need to be judged less by asset class labels and more by the economic risks each holding is designed to address.
Five portfolio considerations for a higher-cost-of-capital world
1. Be more deliberate about duration
Long-duration bonds can still play a vital role, particularly if an oil shock ultimately weakens growth. But they shouldn’t be seen as the portfolio’s default shock absorber.
Higher inflation volatility, heavy Treasury issuance, and a potentially higher term premium may favor a more balanced maturity profile rather than one large directional bet on rates.
The key distinction is why rates are moving. A growth shock and an inflation or fiscal shock can have very different implications for long bonds.
2. Build in explicit inflation sensitivity
If nominal bonds can’t hedge every inflationary shock, other sources of inflation resilience may warrant consideration.
Inflation-linked bonds, commodities, and certain real assets can respond differently when inflation surprises to the upside. Infrastructure may also play a role, where assets have pricing power or contractual inflation adjustments.
There is no universal inflation hedge, however. Selection still matters.
3. Focus on balance-sheet resilience
A higher cost of capital doesn’t affect every company equally.
Businesses with pricing power, strong free cash flow, resilient margins, and manageable leverage may be better positioned to absorb higher energy, freight, and financing costs.
In credit, refinancing schedules, leverage, cash generation, and balance-sheet flexibility may become increasingly important as weaker borrowers face higher funding costs.
4. Broaden the sources of diversification
If inflation shocks can hurt stocks and nominal bonds simultaneously, portfolios may benefit from additional return drivers.
Depending on objectives and constraints, those could include macro, absolute-return, long/short, or multi-strategy approaches, as well as selected real assets and inflation-linked securities.
The goal is not to find one asset that hedges everything but, rather, to avoid asking one bond allocation to offset every portfolio risk.
5. Preserve liquidity
In a world where inflation, rates, and credit can be repriced quickly, liquidity has value beyond its yield.
Cash, Treasury bills, and other high-quality short-duration fixed income assets can give investors room to rebalance, meet spending needs, and act when opportunities emerge without having to sell other holdings under pressure.
Building resilience for more than one outcome
None of these considerations requires getting one macroeconomic forecast exactly right.
Different exposures can play different roles depending on the shock: long-duration bonds if growth deteriorates, short-duration assets when inflation and term-premium risk are elevated, inflation-sensitive assets when supply shocks dominate, and companies with stronger balance sheets when financing becomes more expensive.
The broader point is that the next shock may not look like the last one.
The recent oil shock has put inflation and the Fed back in focus, but its larger significance may be what it reveals about a much more structural shift: Energy, fiscal policy, Treasury supply, geopolitical fragmentation, and private investment are all influencing the cost of capital.
For investors, the more useful question may therefore be:
How much of my portfolio depends on inflation falling and interest rates coming down?
If the answer is “a lot,” that may point to a vulnerability worth examining.
The views expressed are those of the authors at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.
Expert
- Vice Chair and Head of Sustainable Investment

- Fixed Income Portfolio Manager



Monthly Market Review — July 2026
A monthly update on equity, fixed income, currency, and commodity markets.
By