Italy, Institutional
Change

Equities
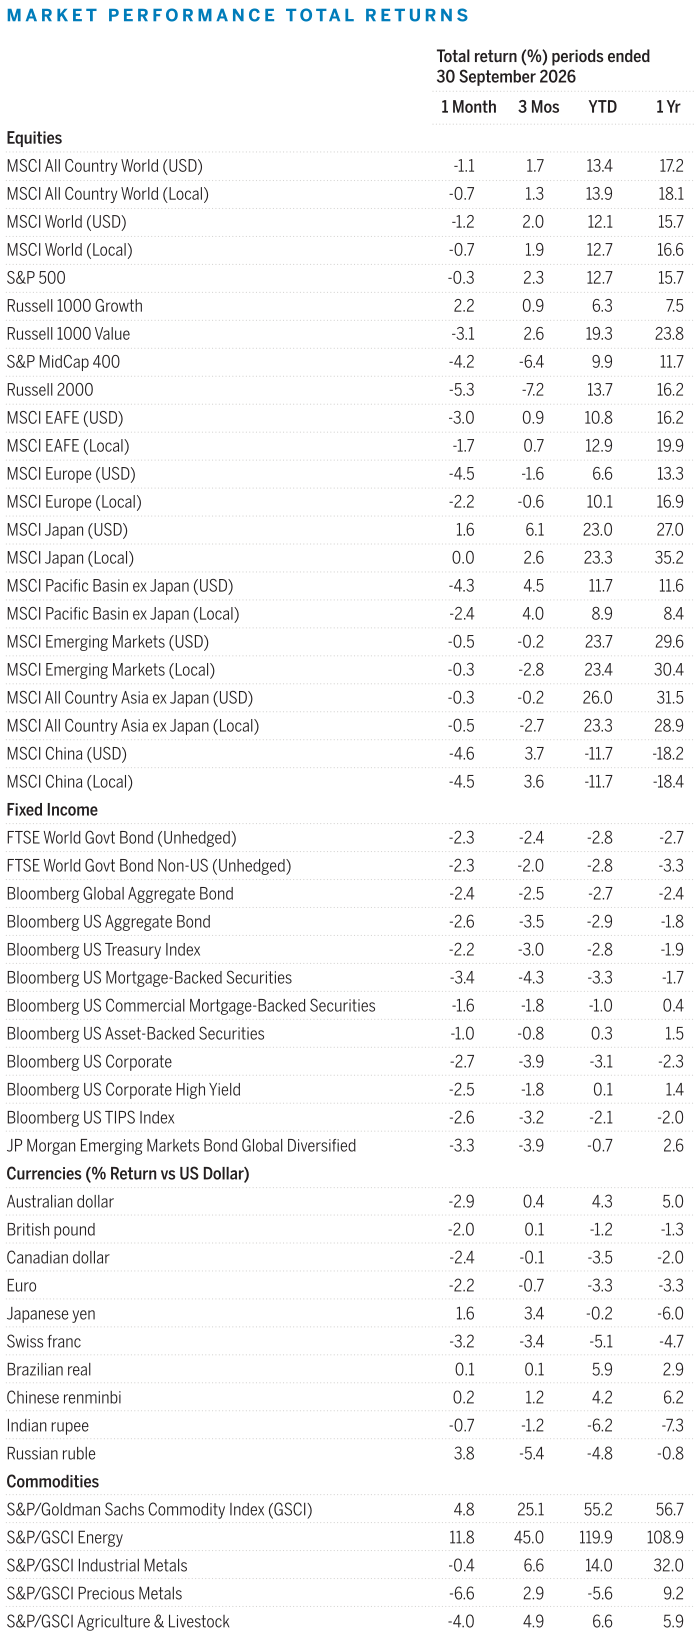
Global equities (-0.7%) declined in September as rising bond yields and persistent inflation weighed on valuations, partly offset by robust demand for AI infrastructure. S&P Global’s preliminary September business surveys identified AI investment, defense spending, and consumer demand as sources of growth, as its GDP-weighted G4 Composite Purchasing Managers’ Index (PMI) Output Index showed aggregate business activity across the US, the eurozone, Japan, and the UK expanding at its fastest pace since March 2022. This expansion coincided with rising cost pressures; US businesses reported the fastest increase in input costs since October 2022, while input-cost inflation also accelerated in the eurozone and the UK. Stronger activity and elevated inflation reinforced expectations of tighter monetary policy, contributing to higher bond yields and financing costs. The conflict in the Middle East added to inflation risks through elevated energy costs, placing additional pressure on businesses and households in energy-importing economies. Corporate earnings results released during the month highlighted continued demand for computing infrastructure, supporting earnings prospects at key technology suppliers. In China, economic data released in September showed strong exports and expanding high-technology manufacturing alongside subdued retail sales and declining property investment.
US
US equities (-0.3%) were largely unchanged despite weakness across most sectors of the economy. Gains in the technology and communication services sectors offset sharp declines in financials, materials, real estate, utilities, and consumer discretionary, as surging US Treasury yields and highly elevated energy prices weighed on areas of the market that are sensitive to interest rates. Against this backdrop, growth and large-cap stocks significantly outperformed their value and small- and mid-cap counterparts. A solid labor market, a sizable rebound in consumer spending, and expansionary activity across the manufacturing and services sectors provided impetus to the economy, but persistent inflation and tightening financial conditions are key concerns. The US Federal Reserve (Fed) raised interest rates by 25 basis points (bps) — the first increase since 2023 — and a vast majority of Fed officials projected another hike this year. Second-quarter annualized GDP was revised significantly higher to 2.2%, while annual core Personal Consumption Expenditures inflation increased to 3.0% in August, below expectations but still well above the Fed’s target. Analysts and companies are increasingly optimistic about third-quarter earnings, with earnings for companies in the S&P 500 Index forecast to grow 29.5% year over year.
Economic data released during the month was mixed but the economy remained on a solid footing. A sizable rebound in job growth helped to ease concerns of a rapidly slowing labor market. August nonfarm payrolls surged by 162,000, more than double economists’ expectations and well above the 12-month average monthly gain of 31,000. Importantly, a 55,000 upward revision to job growth in the prior two months suggested that the labor market had cooled more modestly than initially thought. The unemployment rate was steady at 4.1%, and initial jobless claims remained exceptionally subdued. In contrast, wage growth was the slowest since 2001, while job openings slipped to a five-month low, suggesting that employers remained cautious about hiring. Consumer spending rebounded in August on the back of a stable job market and recent stock market gains. Retail sales grew at a robust 1.2% monthly pace following a 0.5% decline in July, while personal spending increased by 0.6%, the largest gain since March 2025. However, in September, the Conference Board’s Consumer Confidence Index deteriorated to its lowest level since April 2014 amid anxiety about high energy prices, rising interest rates, and elevated inflation. The housing market continued to weaken as mortgage rates hit a nearly three-year high.
The manufacturing sector expanded at a solid pace in September, with the Institute of Supply Management (ISM) Manufacturing Index ending at 54.5. New orders and employment grew at a faster clip, and a sharp rise in input prices reflected inflation pressures from elevated energy prices. In August, the services sector showed robust momentum across sectors, as the ISM Services Index climbed to 55.4. Inflation pressures rose, new orders growth accelerated to the fastest pace since early 2023, and business activity was the strongest since 2022. The NFIB Small Business Optimism Index showed that sentiment eased slightly but remained relatively elevated.
Within the S&P 500 Index (-0.3%), 9 of the 11 sectors posted negative results for the month. The financials sector was the worst performer, led lower by capital markets (-9.9%) and banks (-7.3%). Materials (-6.7%) and real estate (-6.1%) also underperformed the index. Information technology (+4.5%) was the best-performing sector, while communication services (+4.5%) also outperformed.
Europe
European equities (-2.2%) registered their first monthly loss in six months, as the ongoing energy-driven inflation shock and surging bond yields weighed on markets. Despite intensifying price pressures and rising energy costs, the eurozone economy proved surprisingly resilient. The S&P Global Flash Eurozone Composite PMI climbed from 52.0 to 53.1 in September — the highest since April 2023 — thanks to accelerated growth across the manufacturing and services sectors. German output expanded at its fastest pace in almost a year, while French business activity returned to growth for the first time in 10 months. In response to upward inflation pressures and the risk of a lengthy period of elevated energy prices, the European Central Bank (ECB) raised interest rates for the second time this year. The decision exacerbated a government bond sell-off, which drove borrowing costs in Germany and France to their highest levels since 2011 and 2008, respectively. Norway’s central bank also raised interest rates, while the central banks of Sweden, Switzerland, and the UK left policy unchanged. Annual eurozone headline inflation rose more than expected to a three-year high of 3.8% in September, increasing pressure on the ECB to raise interest rates again by year end. Eurostat estimated that annual energy inflation climbed to 18.8%, up from 14.3% in August. According to LSEG, second-quarter earnings for companies in the STOXX 600 Index are forecast to increase by 23.9% from a year earlier.
The S&P Global Eurozone Manufacturing PMI climbed for the third consecutive month to 52.9 in September — the highest level since May 2022 — as resilient demand drove new orders and output to multiyear highs. The S&P Global Flash Eurozone Composite PMI revealed that services sector activity expanded noticeably to a 10-month high. Inflationary pressures intensified, with both input costs and output prices increasing at the fastest rates in four months. The European Commission’s Economic Sentiment Indicator declined mildly to 97.9 in September; industry confidence improved, while consumer confidence weakened.
In Germany (-4.0%), strong growth in production and new orders in September helped to sustain the country’s manufacturing upturn. The ZEW Indicator of Economic Sentiment edged up in September to its highest level since February amid optimism about Germany’s economic recovery, which is expected to remain supported by fiscal stimulus and measures to boost exports. The UK’s (-2.0%) economy grew at a stronger-than-expected 0.4% monthly pace in July (1.6% annually), supported by the services sector. However, the S&P Global Flash UK PMI Composite Output Index indicated that growth slowed in September as momentum weakened across both manufacturing and services. Annual headline inflation accelerated to a five-month high of 3.1% in August, driven by rising energy prices, while core inflation was steady at 2.6% for the fourth straight month. The Bank of England warned that it may raise interest rates if higher inflation becomes entrenched in the economy.
Pacific basin
Pacific Basin equities (-0.7%) fell over the period. In Japan (+0.0%), expectations of a Bank of Japan (BOJ) interest-rate hike in September — reinforced by hawkish comments from BOJ board members and repeated calls from US Treasury Secretary Scott Bessent for tighter policy — briefly supported the yen and pushed bond yields to multi-decade highs. The case for higher interest rates strengthened as second-quarter GDP was revised higher, nominal wage growth reached its fastest pace since 1997, corporate input costs remained elevated, and August exports stayed robust. However, stagnant consumer spending and persistent cost-of-living pressures remained key risks to the economic outlook. Japan’s underlying inflation trend remained solid, even as core inflation slightly decelerated to 1.7% in August, with government fuel subsidies offsetting rising import costs from a weak yen and surging oil prices. Against this backdrop, the BOJ raised its benchmark rate by 25 bps to 1.25% in a 7 – 2 vote, as widely expected. However, two dissenting votes from “reflationists” on the BOJ’s board, along with signs that inflation is relatively contained, weakened the yen and reduced market expectations for a consecutive October rate hike.
In Australia (-2.2%), higher-than-expected unemployment in August briefly tempered rate-hike expectations; by contrast, higher-than-forecast second-quarter economic growth, alongside surging energy costs and resilient household and business demand, kept pressure on the Reserve Bank of Australia (RBA) to tighten policy. The central bank unanimously raised interest rates by 25 bps to a 15-year high of 4.6%, citing persistent inflation risks. Despite upside inflation risks, markets scaled back expectations for another hike in November following RBA Governor Michele Bullock’s measured tone and softer-than-anticipated inflation in August. Annual headline CPI rose 4.0%, below expectations of 4.5%, while core inflation was unchanged at 3.6%.
In Singapore (-2.3%), economic momentum remained supported by strong external demand, as non-oil domestic exports surged 46.2% and electronics exports rose by a record 132% year over year in August on robust AI-related demand. However, softer retail sales and lower-than-expected industrial production pointed to uneven domestic activity. Headline and core inflation accelerated to 2.3% and 2.2%, respectively, increasing expectations of modest policy tightening, although contained price pressures and a divided economic outlook could limit the scope for action by the Monetary Authority of Singapore.
In Hong Kong (-3.3%), the Hong Kong Monetary Authority raised interest rates by 25 bps to 4.25% — the first hike since 2023 — to maintain the Hong Kong dollar’s peg to the US dollar. Domestic conditions improved as August exports rose more than expected at 53% year over year and imports surged 60.0%, although higher borrowing costs and tighter mainland capital controls threatened the property market’s nascent recovery.
Emerging markets
Emerging markets (EM) equities (-0.3%) ended the month slightly lower. Europe, the Middle East, and Africa (EMEA) led the decline, followed by Asia, while Latin America gained.
In EMEA (-3.3%), Saudi Arabia’s (-5.8%) economy came under pressure after drone attacks temporarily shut down the strategically important East-West Pipeline and threatened a key oil export route, pushing global energy prices higher. However, the Riyad Bank PMI rose to 55.3 from 53.8 in August, as non-oil private sector activity expanded at the fastest pace since February. South Africa (-7.2%) suffered its first economic contraction in nearly two years. Second-quarter GDP declined 0.2% amid weaker domestic demand and higher imports due to the conflict in Iran, alongside underperforming mining and manufacturing sectors.
In Asia (-0.1%), China (-4.5%) declined amid mixed economic data. Retail sales grew only 0.4% year over year in August, much worse than consensus and the slowest pace since May, while fixed-asset investment plunged 7.2% in the first eight months of 2026 compared to the same period last year. However, services activity in September increased at the fastest pace in three months, and factory activity expanded at a modest rate. Exports supported industrial activity and remained strong, increasing 25% year over year in August thanks to surging demand for high-tech and AI-related products. Policymakers introduced new measures to support economic growth and the struggling property sector, including targeted bank lending and new subsidies for homebuyers’ mortgage interest payments, as officials worked to achieve the government’s year-end growth target of 4.5% – 5.5%. Taiwan’s (+4.5%) economy remained well supported by AI-related technology, semiconductors, and electronics exports. Manufacturing activity accelerated at the fastest pace in more than five years, with the S&P Global Taiwan Manufacturing PMI rising to 56.7 in September. Exports hit a record high of US$81.4 billion in August, up 41% year over year. In South Korea (+2.0%), exports in September soared 83.5% from a year earlier to an all-time high of US$120.9 billion, as semiconductor shipments more than tripled on robust global AI-related spending. India (-6.3%) was dragged down by record foreign outflows, soaring crude prices, and rising global bond yields. Consumer price inflation accelerated for the tenth straight month to 4.82% in August, with broadening price gains pressuring the central bank to raise interest rates.
In Latin America (+1.3%), Brazil (+3.1%) advanced despite signs of moderating economic momentum. The Finance Ministry lowered its 2026 GDP growth forecast to 2.0% from 2.3%, citing lower services and industrial activity, while the central bank continued its easing cycle with a fifth consecutive 25 bps interest-rate cut to 13.75%. Annual inflation subsequently accelerated more than expected to 4.47% in September, stoking voter anxiety ahead of a tightly contested presidential election in October. In Mexico (-1.5%), annual inflation rose to 3.42% in September, although core inflation continued to trend lower. The S&P Global Mexico Manufacturing PMI edged back into expansionary territory at 50.3 in September.
Fixed Income
Global sovereign bonds sold off in September as higher oil prices revived inflation concerns and resilient economic data reinforced expectations of tighter monetary policy. The Fed, the ECB, the BOJ, the RBA, and the Reserve Bank of New Zealand each raised policy rates by 25 bps. The Bloomberg Global Aggregate Index returned −1.64% in US dollar-hedged terms, underperforming duration-equivalent government bonds by 0.25 percentage points, according to the Bloomberg figures.
US Treasuries led the rise in sovereign yields as the 10-year yield climbed 54 bps to 5.29%. UK gilt yields rose amid fiscal concerns ahead of the October budget, while German and French bonds also weakened. Japanese government bond yields increased more modestly following the BOJ’s rate rise.
Credit offered little relief. US investment-grade corporate bonds posted negative total returns but performed broadly in line with duration-equivalent Treasuries. High yield lagged as spreads widened more sharply. EM hard-currency debt also declined as higher US Treasury yields weighed on returns.
Currencies
The US dollar strengthened against most major currencies as expectations of further Fed tightening rose. The New Zealand dollar led the declines, pressured by US dollar strength and higher oil prices that clouded the economic growth outlook. The Swedish krona, Swiss franc, and Australian dollar also weakened. The Japanese yen outperformed, supported by a more hawkish tone from the BOJ and renewed warnings of currency intervention. EM currencies broadly declined as higher US Treasury yields and a stronger dollar dampened risk appetite. The Mexican and Colombian pesos were among the weakest, while the South Korean won gained on continued export strength.
Commodities
Commodities (+4.8%) continued to rise in September, driven by energy. Precious metals, agriculture & livestock, and industrial metals detracted from performance.
Energy (+11.8%) rallied. Gas oil (+16.7%) led the gains as disruptions to Middle Eastern exports, reduced refinery feedstock availability, and record-high distillate margins tightened diesel markets. Gasoline (+12.5%) advanced as resilient transportation demand coincided with lower product inventories and concerns about fuel availability due to shipping disruptions. Crude oil (+11.7%) rose as substantial Gulf production remained offline amid heightened security risks, contributing to global inventory drawdowns and tighter physical markets. Heating oil (+10.9%) benefited from strong distillate demand, constrained refinery production, and low inventories ahead of the Northern Hemisphere heating season. Natural gas (-1.4%) weakened as adequate storage and an improving supply outlook weighed on prices. The lifting of a late-September force majeure on the Mountaineer XPress pipeline restored Appalachian flows to downstream markets.
Industrial metals (-0.4%) declined modestly. Copper (+1.1%) was supported by demand from power grid expansion, electric vehicle production, and renewable energy investment. Expectations of tighter supply and uncertainty over potential US tariffs on refined copper also encouraged inventory shifts. Zinc (+0.0%) was flat, as tight supply and low inventories were offset by concerns about slowing industrial demand. Aluminum (-1.7%) declined, with worries about global manufacturing outweighing support from falling London Metal Exchange inventories and warehouse withdrawals. Lead (-2.0%) weakened on lower demand and reduced purchases from battery manufacturers. Nickel (-5.7%) was dragged down by rising Indonesian production, reinforcing concerns about global oversupply. Additionally, ample refined nickel supply and softer battery-sector demand expectations weighed on prices despite the metal’s long-term role in electrification.
Precious metals (-6.6%) weakened. Gold (-6.3%) declined as higher Treasury yields increased the opportunity cost of holding the metal, in addition to reduced safe-haven demand. Silver (-9.3%) fell more sharply as those same pressures were compounded by weaker expectations for industrial demand.
Agriculture and livestock (-4.0%) ended lower. Feeder cattle (+7.3%) and live cattle (+3.9%) advanced as tight US herd inventories and persistent supply constraints supported prices, while strong demand from cattle feedlots added momentum to feeder-cattle prices. Soybeans (+0.7%) posted a modest gain on higher export demand, while wheat (-12.4%) was pulled lower by improved harvest conditions, strong crop yields, and forecasts for abundant global supplies. Anxiety about softer import demand, including from China, put further pressure on wheat. Cotton (-15.4%) declined amid worries about slowing textile demand and near-term inventory availability. Cocoa (-20.5%) plummeted as elevated prices stoked concerns about weaker consumption and reduced manufacturer purchases. In addition, expectations of slower processing heightened fears of demand destruction.
The views expressed are those of the authors at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.






Quarterly Market Review — 3Q26
A quarterly update on equity, fixed income, currency, and commodity markets.
By