United Kingdom, Professional
Change
Key points
- After an extended period of narrow growth-led market leadership, we may be entering a new era where value reasserts itself.
- A shifting economic and industrial landscape with greater demand for increasingly constrained capital is likely to drive greater cyclicality, which active value investors may be able to exploit.
- Key, in our view, is the ability to identify quality businesses that are temporarily out of favour but combine strong longer-term potential with attractive valuations and clear catalysts for recovery.
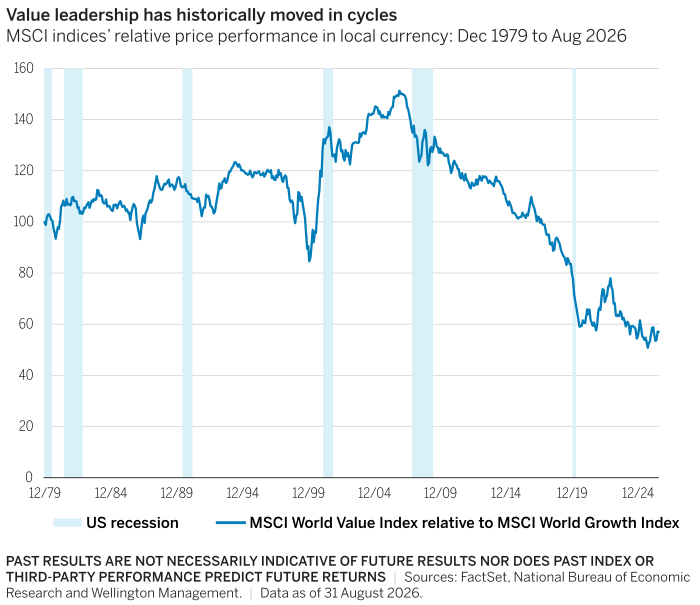
While the AI story continues to steal the limelight, a broader shift in the conditions that shaped the last decade’s equity market winners is also underway. Value and growth leadership have historically moved in long cycles, but the post-financial-crisis period was unusually prolonged in its support for growth, as cheap capital, low inflation and globalisation rewarded asset-light businesses and long-duration earnings. As Figure 1 shows, that period stands out against a much longer history of shifting market leadership. We believe today’s higher capital costs, shifting industry economics and more consequential market cycles are creating a more supportive backdrop for value once again.
Global equity indices remain concentrated and growth-leaning, while parts of the market are still priced on demanding assumptions about future earnings. Value offers diversification from that concentration, but the case for value investing today goes well beyond simply buying cheaper stocks. The economic environment itself is changing.
Figure 1
Why industry cycles matter again
The decade after the global financial crisis was characterised by cheap capital, globalisation and low inflation. Today, higher capital costs, reindustrialisation and more persistent inflation pressures are putting greater emphasis on physical capacity, the ability to pass on costs and capital discipline. This more constrained backdrop could also produce more frequent shifts in industry profitability as companies respond to shortages, excess capacity and changing demand.
That matters because companies and industries are self-correcting. When demand exceeds supply, prices and margins rise, attracting investment and new capacity. When supply exceeds demand, prices fall, weaker capacity exits and investment is cut. Those adjustments ultimately sow the seeds of the next cycle.
The current semiconductor memory market provides a useful illustration. A sharp rise in PC memory prices, as shown in Figure 2, is now being met by accelerating capital expenditure by a market-leading supplier. Scarcity encourages supply, and that response may ultimately change who benefits across the value chain.
Figure 2
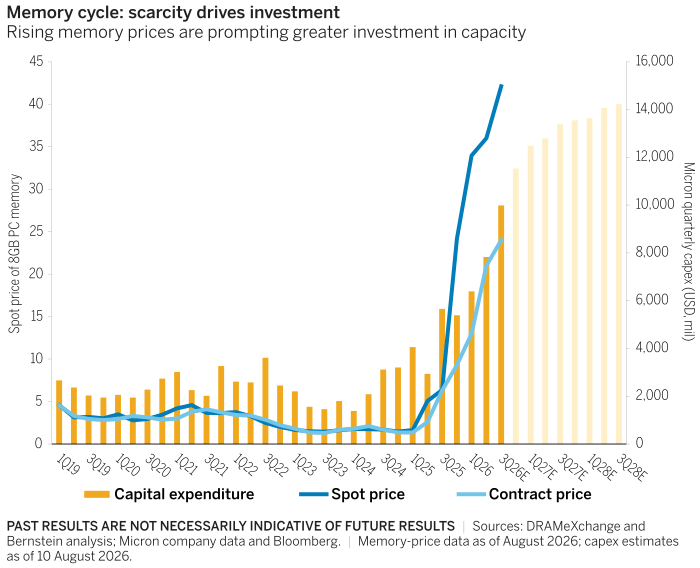
Markets often struggle to price these turning points. Investors naturally tend to extrapolate current trends, assuming strong earnings will stay strong and weak earnings will persist. At cyclical troughs, this can push share prices below levels justified by a company’s longer-term earnings power; at peaks, the reverse can occur.
Finding attractive opportunities in the next cycle
In this environment, we think active value investing can be particularly compelling. Of course, cheapness alone is not enough: some companies are inexpensive because their businesses are in structural decline. The opportunity is to distinguish temporary under-earning from permanent impairment and invest before the market fully recognises the difference.
In our view, a focus on quality is key to making the most of this opportunity. Specifically, we think value companies with the greatest potential combine three things:
- an attractive valuation based on normalised earnings;
- sufficient quality to withstand the cyclical trough; and
- an identifiable catalyst that can help unlock value over a reasonable time horizon — say, two to three years.
We believe the potential of such an approach is particularly pertinent as the market regime changes. Many of the asset-light businesses that led markets after the global financial crisis were able to compound strong returns while requiring relatively little capital to grow. AI is now challenging parts of that landscape, given its potential to disrupt established business models. In response, several former asset-light leaders are having to (re)invest heavily to defend or extend their competitive positions. Much of this AI investment is directed towards the physical infrastructure needed to support it.
This new trend creates an interesting contrast. Many businesses tied to the physical economy are inherently cyclical, but their productive capacity cannot be created instantly. Where years of weak profitability have discouraged investment, even modest changes in demand can expose supply constraints and drive significant earnings recoveries.
For us as value investors, these are exactly the kinds of turning points in the cycle that can create attractive opportunities — for both asset-light and physical businesses. The two examples below illustrate what that may look like in practice.
Example one: We believe that some of the initial losers from increasing memory prices are now set to benefit as memory supply ramps up. Take, for instance, this personal computing provider, where higher memory costs and a lag in passing through price increases are depressing PC margins. This challenging setup has resulted in near-term earnings falling below what we believe the business can generate through a more normal cycle. The shares trade at a low valuation on these depressed earnings, while its large global franchise, strong commercial exposure and resilient free cash flow provide the required underlying quality. A stabilisation in memory costs and evidence that pricing and margins are beginning to recover could be the catalyst for share price outperformance.
Example two: We believe that narrow market leadership has left attractive opportunities in high-quality businesses tied to the physical economy that have been on the sidelines. An example we particularly like is a US-based water technology company providing infrastructure, water treatment, leakage detection and water efficiency solutions. Ageing infrastructure, increasing water scarcity and growing pressure on water systems are supporting long-term demand, while the company’s relatively stable earnings and cash flow offer the financial resilience we look for. The shares trade at an attractive valuation, and we believe rising investment in water infrastructure could support stronger earnings over time. Evidence that this demand is translating into improving earnings growth could provide a catalyst for share price outperformance.
Key takeaway for investors
For investors, the case for global value today is about more than low valuations. A more constrained and cyclical world could create larger shifts in earnings and industry economics, while AI may challenge some of the asset-light winners of the previous decade. This combination may help to create attractive opportunities for investors who can identify businesses that are mispriced against their earnings potential.
The views expressed are those of the authors at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.
ExpertS

- Equity Portfolio Manager, Equity Boutiques

- Equity Research Analyst, Equity Boutiques

- Investment Specialist, Equity Product Management
Related funds



Monthly Market Review — August 2026
A monthly update on equity, fixed income, currency, and commodity markets.
By