Formats
2026 Midyear Investment Outlook

2026 Midyear Investment Outlook
Income, inflation, and employment remain essential to understanding the US consumer and economy. But household wealth increasingly belongs on that list. Financial assets are concentrated among affluent households, while millions of baby boomers are entering retirement with substantial holdings in equities, property, and other assets. Together, these forces are strengthening the link between financial markets and economic activity and creating opportunities and risks for investors.
Historically, consumer spending has fueled the economy, accounting for about two-thirds of GDP. The highest-income households have generally accounted for about 35% of that spending, but today that understates reality because it ignores the growing role of financial wealth: The top 20% of households own 87% of US equities, so rising markets can expand their capacity to spend.1 Taking this wealth effect into account, I estimate that the top 20% of households currently account for about 50% of total consumer spending.
This suggests that consumption may remain more resilient than income-based models imply. It also reinforces the “K-shaped economy.” Affluent consumers can continue spending on experiences and services, while lower-income households remain more exposed to affordability pressures.
Investment implications: Potential industry winners of a durable wealth effect include financial services (e.g., wealth managers), travel and leisure, and parts of health care.
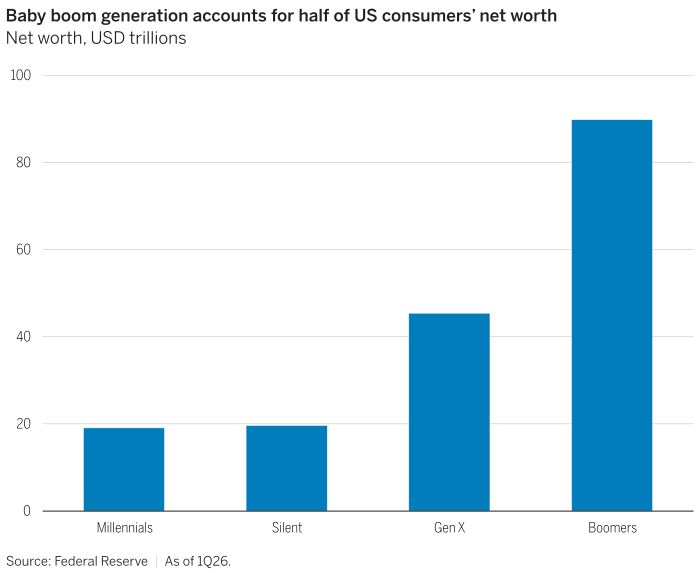
We’re in the midst of a historic demographic transition in the US. Between 2024 and 2027, roughly 10,000 baby boomers turn 65 every day. The wave of Americans reaching retirement age shifts the source of spending from wages toward accumulated assets and government benefits. And those accumulated assets are substantial: Baby boomers control about half of total US household net worth (Figure 1).
That household net worth includes substantial home equity, and many older homeowners have strong incentives to stay put. Selling can mean realizing taxable gains and buying another expensive property, while remaining in place may preserve flexibility and estate-planning advantages. The result is a housing market constrained not only by mortgage rates, but also by demographics and tax considerations.
Investment implications: These trends may favor businesses related to home remodeling over house purchases, as well as aging-in-place and other senior living solutions. Those likely to be relatively disadvantaged include first-time home buyers and businesses tied to strong housing turnover, such as title insurers.
The transfer of wealth that will be driven by an aging population will undoubtedly reshape financial markets, but its effects are likely to unfold gradually rather than deliver a sudden windfall to younger generations. Assets often pass first between spouses, while longevity, health care costs, charitable giving, and taxes can reduce what ultimately reaches their heirs. Because the largest inheritances tend to flow to households that are already affluent, much of the money may remain invested rather than be spent immediately.
Investment implications: Financial intermediaries are likely to be among the clearest beneficiaries. Also, I expect the allocation of wealth across asset classes to shift as younger generations show more enthusiasm for private assets or crypto assets relative to older generations.
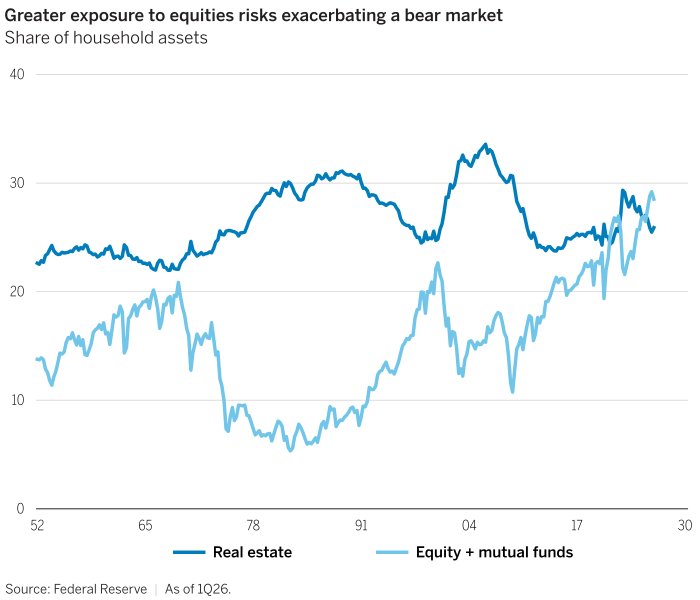
Increasing reliance on financial assets makes the economy more sensitive to market declines (Figure 2). A sustained equity downturn could weaken affluent-household spending, prompt retirees to become more defensive, and reduce government tax receipts for capital gains at the same time. The transmission from markets to the real economy may therefore be stronger than in past cycles.
Investment implications: First, consider strengthening downside protection. For example, some long/short and hedge fund strategies may offer greater resilience in an equity market drawdown. Second, look for opportunities to broaden diversification across asset classes and geographies. Real assets, for instance, may enhance diversification in a traditional stock/bond portfolio. Finally, adopt a rotational mindset. A meaningful decline in wealth would change spending, earnings, and market leadership, which could reverse the fortunes of many of the potential winners and losers discussed above. Portfolio flexibility may therefore be as important as portfolio protection.
1Source: Federal Reserve, Survey of Consumer Finances
The views expressed are those of the author at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional or accredited investors only.