
- Global Investment Strategist
Australia & NZ, Institutional & Wholesale
Change
The views expressed are those of the author at the time of writing. Other teams may hold different views and make different investment decisions. The value of your investment may become worth more or less than at the time of original investment. While any third-party data used is considered reliable, its accuracy is not guaranteed. For professional, institutional, or accredited investors only.
Gold is a provocative topic these days. First, there’s the incredible 52% run-up in the price of gold through the first 10 months of the year.1 Second, there’s the unusual coincidence of stocks and gold performing well at the same time. After all, while the recent strong returns of stocks would seem to reflect a positive outlook for risk, doesn’t the rise in gold, usually considered a hedge against risk, suggest the opposite?
I think the gains in stocks and gold are indeed saying different things, but I also believe holding them both makes sense in the current environment. Even if stocks continue to do well, I see three reasons that gold can still play a potentially helpful role in portfolios over the next few years:
1. Gold and stocks have different drivers in today’s market environment
In the past, gold’s performance has generally been tied to one of several drivers, including demand for a “safe haven” asset amid economic or geopolitical volatility or a “store of value” asset given worries about currency devaluation or inflation. But today, I would argue that gains in gold have been tied to a range of drivers that could be with us for some time to come, including:
Meanwhile, the rise in stocks has been driven largely by exceptional gains in the mega-cap tech companies dominating the market (as of the end of October, the Magnificent Seven stocks accounted for almost 37% of the market capitalization of the S&P 5002). Along with these strong earnings, stocks are benefiting from easy monetary and fiscal conditions and a decent growth backdrop. In short, the rally in stocks and gold is not the same “trade.”
2. Demand for gold is expanding
Central bank demand for gold has been well-documented. After the US government placed sanctions on Russian US-dollar assets, for example, central banks, especially in emerging markets, sought to diversify their currency reserves away from the US dollar. Retail demand in China has also played a role after that country’s real estate bubble burst. More recently, we’ve seen growth in US and European retail demand for gold reflected in the surge in ETF holdings this year.
3. Including gold in a portfolio could improve its overall risk/reward profile
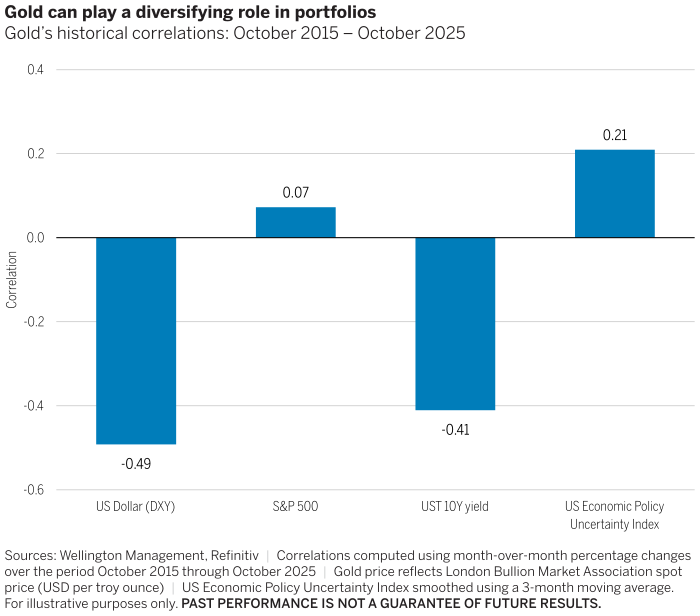
That’s because gold has tended to have a low correlation to risk assets and lower volatility. Figure 1 shows that gold has had a near-zero correlation to US stocks, a negative correlation to the US dollar and bond yields, and a positive correlation to policy uncertainty over the past 10 years. Results are similar for global stocks and bonds, as well.
Figure 1
What are the potential risks? Given gold’s meteoric rise this year, I think it’s expensive based on various metrics, including the real (inflation-adjusted) price of gold and the ratio of gold’s market cap to global GDP, among others. Also, gold generates no cash flow or yield — a potential downside relative to cash holdings.
What happens to gold if stocks go down? It depends on the cause. If stocks sell off because inflation induces the Fed to hike interest rates, then I would expect gold to decline. If, however, stocks fall because of recession fears, then I think gold is likely to outperform stocks.
Gold may be an effective hedge in multiple downside scenarios — While I still believe fundamentals are generally favorable for stocks, I think allocators with substantial exposure to them should consider diversifying, and that gold can play a role in that diversification effort. As noted, US stocks are benefiting from the AI boom, but there are potential economic risks to consider, from stagflation to issues around US debt and central bank independence. In addition to potentially offsetting downside risk in stocks, gold may help hedge against other risks, including inflation and currency devaluation.
Allocators may want to consider broader exposure to diversified commodities — Since gold currently looks expensive on various metrics, a broader portfolio of commodities that includes precious metals, industrial metals, energy, and agriculture could be an alternative. Beyond the benefits of gold, I see signs of a broader commodities “super cycle” emerging, driven by rising power demand and a lack of supply in a host of commodities critical to the AI expansion.
1Source: Refinitiv. Gold price reflects London Bullion Market Association spot price (USD per troy ounce). | 2Source: Refinitiv. Magnificent Seven stocks include Meta, Alphabet, Tesla, NVIDIA, Amazon, Apple, and Microsoft.



Monthly Market Review — September 2026
A monthly update on equity, fixed income, currency, and commodity markets.
By